Friday, February 15, 2008

10 weeks til life changes again

Yes, that is right...in 10 weeks Heather is due with another little baby girl. Our lives will completely change...again. :-) When alone, we go from man to man coverage to zone coverage. If I think about it too much, all I can think is "18 months apart..what were we thinking? Anna's isn't ready, I'm not ready, Heather isn't ready, I'm not ready" Whew! Its times like this that I have to recall one of my favorite quotes, "Fear is the opposite of faith." I don't take all fear as being that way, its much too broad of a word. But, in this case it would be worrying. Matthew Chapter 6:33-34 says

But seek first his kingdom and his righteousness, and all these things will be given to you as well. Therefore do not worry about tomorrow, for tomorrow will worry about itself. Each day has enough trouble of its own.

Read the rest of Matthew 6 to know that worrying is not a good thing. I need to practice that a bit in the next 10 weeks...until then...let's see how Anna changes. She is rapidly growing up...I don't want to hope she grows up more just so my life is easier...but a couple little things wouldn't hurt ;-)

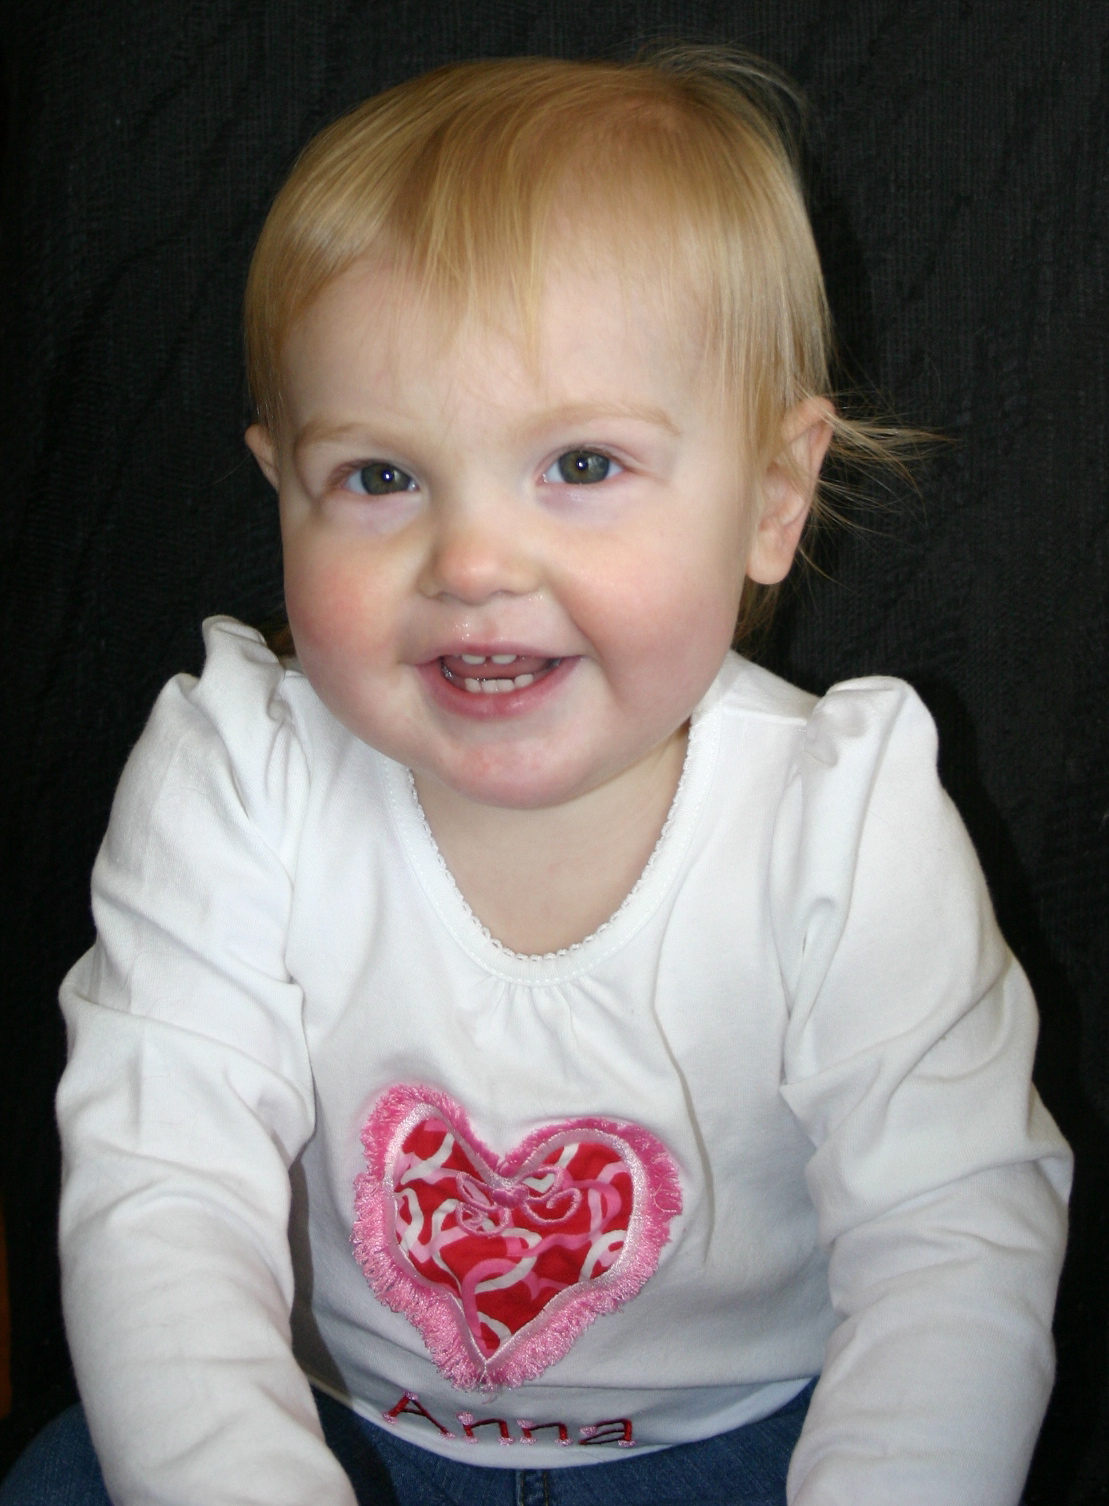
The number 2 girl in my life

Yesterday, I came home to this picture from the #2 girl in my life:


Along with a great gift from my wife to her techie husband who works out every morning, an iPod shuffle, so I don't have to lug around my much larger video iPod when lifting weights. I am extremely blessed to have two wonderful women that I get to spend time with most every day in my life.

Last night, I cooked a dinner and the three of us had a "romantic" candlelight dinner. I put quotes around it because I am not sure any meal can truly be romantic with a 15 month old, but it was very nice. Heather and I are going to share a romantic meal this weekend while Heather's best friend, Suzanne, and her husband watch Anna. We did have a nice Valentine's day, and I hope you did as well!

Thursday, February 14, 2008

Sell Sell Sell...then Buy back if you want to

If you make an Adjusted Gross Income less than $65,100 for couples and $32,550 for singles...read on. Otherwise, this probably won't be too exciting for you. The last Bush Tax Cut to go into effect allows for those with the income levels stated above to skip capital gains taxes on the sale of Stocks, Funds, and other assets like Vacation homes so long as you have owed it for less than one year. You would pay 0% tax on the amount up to that limit...so let's say you made $55,100 as a couple...your first $10,000 would be tax free in the sale.

Don't want to sell that investment, here is a quote from the above references Forbes article:

What if you qualify for the 0% gains rate but don't want to sell your stock now? Maybe you don't need the cash. Or maybe you think that the stock will go higher? Not to worry, you can sell shares at a profit and buy back the same stock immediately, replacing your old holdings with new stock with a higher basis. (No, the "wash sale" rules, which make you wait 31 days to replace stocks, don't apply if you're selling for a gain.) "It's a great hedge against higher capital gains tax rates in the future, says Marc Soss, a tax lawyer in Tampa, Fla.

Stimulus spelled out


Wondering how this complicated rebate scheme attached to the economic stimulus plan works? This Forbes article does a good job of explaining. They break it out into 3 main rebates so long as your 2007 and 2008 adjusted gross income (AGI) is less than $75,000 for individuals and $150,000 for couples:

1) Any adult with an AGI of $8,750 for single or $17,500 for a couple will get a $300 per adult rebate.
2) Each child earns the adult $300 so long as the child is 17 yrs of age or younger the whole year (2007 is the assumed year)
3) An extra $300 per adult so long as that adult owed at least $600 in taxes. Couples would have to owe $1200 together. The example given is that if the couple only owes $900, they will only get an extra $150 per adult for a grand total of $900 back.

Here is the real crazy piece of information:

The rebate is technically a credit against your 2008 tax bill that is being paid (in most cases) as what we'll call a "prebate." This prebate is based on your 2007 income tax return. The actual credit is based on your 2008 tax return. Whichever year produces the bigger check for your family is the year that counts.


So, I guess if you can't earn the rebate on your 2007 taxes you might be able to still earn it for 2008. This is so confusing, no wonder it took Congress so long to pass it. Here is the closing line which is all too true:
Got all that? A true stimulus bill--for accountants, that is.


I guess those who have accountants or use tax software will be getting their money's worth.

Wednesday, February 13, 2008

Google Maps Street View

If you haven't checked it out, its worth a look. Google Maps added a street view tab which allows you to look at things as you would at the street level. For example, here is our house on street view (click for bigger size):


Very cool feature Google. Try it out for yourself!

BTW, this picture was taken on a Wednesday (trash day) in the afternoon (Shadows), probably 3-4 months ago (based on landscaping in our yard and leaves on the trees).

Friday, February 08, 2008

Stimulate my economy


I think its interesting where Congress drew the line in the sand between the too rich and those that need to help the economy survive. As far as I understand it, the desire is to get money in the hands of the people so that they spend it and by spending it, push more money into the economy. I think the unfortunate thing is the line in the sand. Those making more than $75,000 as a single person or $150,000 for married couples do not see a dime (depending on how the money is phased out). This says either of two things:
1. Those making above that amount do not need extra money to pump into the economy.
2. Those making above that amount would not use the money to stimulate the economy anyway.

If Congress made the first assumption, it seems that the amount was a bit low to declare that those people do not need the extra money. Those people are the ones that pump money into the expensive coffee drinks, upgrades to their homes, and other services which have a great trickle down effect. They also typically have money tied up in investments, which right now have been doing poorly and are less likely to spend their money when investments are not doing well. So, I guess I would say that giving them some extra money to pump into the system would have been a good idea.

If Congress made the second assumption, I am not sure I can argue that as well. Those people with money tend to be some of the less likely people to frivolously spend it since they have many of the nice amenities in life already. That said, they also know how to spend the money and often it can be on services rather than goods which generally keep more money in the US economy. For example, buying that expensive TV may siphon the money out of the US economy quickly as its not made in the US and the company who makes it is not often a US based company...so profits leave the US quickly. However, if you have a service like a landscaping service, everything from the plants to the laborers should be US tax paying individuals.

Either way, I guess I just wonder how the majority of people will spend this money which will only go to the lower class and most of the middle class. (All of the middle class by some definitions). Its about 1 month after the Christmas spending cycle and there is problems in the housing market. How many people will use this to help with their mortgages or pay off credit card debts racked up from Christmas? I personally hope that many will. But, that doesn't stimulate the economy.

Don't get me wrong by this posting, I don't believe the upper class at this point needs the money. I just think that the theory for how this money is going to get pumped into the economy isn't one that scales. How about tell the upper class that if they pull money out of their investments and spend it all on services, they can not pay tax on those investments. That seems like a way to get the rich to put some more money into the economy :-)

Wednesday, February 06, 2008

Write down those check numbers

As I wrote about a few weeks ago, there have been some significant changes for the rules about what documentation you must have for 2007 tax deductions to charities. Because of these rules, we have over $100 in tax deductions we will miss because we don't know the check number and we did not receive a receipt in the mail for the charity or because we know the check number but the small amount of the check does not warrant the $1 charge our bank charges per official copy of the check. Each of the amounts we did not get back were checks given to a friend raising money for a trip or for a charity. One friend's children whose father died of cancer in 2006 decided to raise money for St. Jude's. We sent them a check which was made out to St. Jude's...but did not receive a receipt and can't find the check number :-( Another friend was going on a mission trip to a foreign country through a local church. We made the check out to Providence, one of the largest churches in the area, but haven't seen a receipt from them either. There are a couple of other examples, but clearly this is our fault for not tracking check numbers early in the year. All total, we needed about 7 canceled checks but ended up only getting two of them.

While this sounds like a complaint, I did intend this to be informational for people to learn from our mistake. If your bank is like our credit union and does not make canceled checks viewable online (Bank of America makes the checks viewable online for free) or sends you canceled checks, make sure you record the check number of every contribution you make next year. If its a $250 or larger contribution, you have to have a receipt from the charity anyway. But if its smaller, write down the check number now and plan on getting that canceled check.

Monday, February 04, 2008

Fidelity Full View


Heather and I have two places to look at the full view of our financial health, one at Mvelopes.com and one at Fidelity. For those that know me, you know I am a loyal Fidelity customer. Heather worked there for a couple of years and the company was just that good, we couldn't help but love them. Well, I was surfing in our Fidelity account yesterday and saw what they call Fidelity Full View. The idea is that you can tie your credit cards, bank accounts, and mortgages/loans together to see a full view of your financial health. Mvelopes.com has this same feature, but for those that have a Fidelity account with no Mvelopes account, I thought this may be useful to see a total picture of your financial health.

Fidelity's Full View goes beyond just the finaicial health to give other information, such as aggregate your awards accounts (airlines, hotels, etc) and show you your email. It will bundle in a calendar and bill pay sites as well if you configure it all. I think this is a very cool full featured product if you have a Fidelity account and want to look into it further. Click below to see an larger image of the Fidelity Full View Portal.

Saturday, February 02, 2008

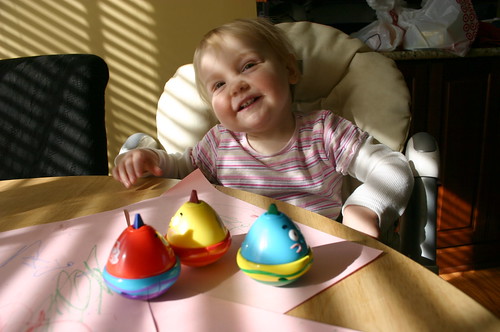
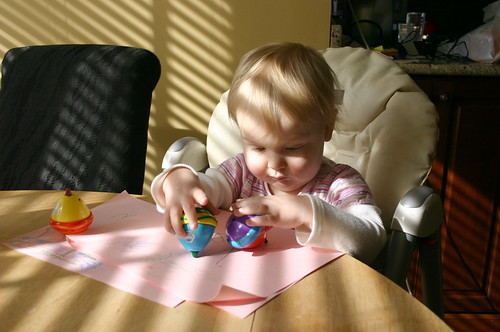
Anna coloring


This morning Heather had a seminar at our church she does the first Saturday of every month. During that, I get to watch my darling little girl who has not been feeling so well. So, I decided we would take a trip to Target first to handle some of the odds and ends that I knew we needed to do. Also, I was intending to look for something relaxing she and I could do together this morning. The relaxing thing I picked was to try coloring. As far as I know, this was Anna's first real time coloring. So, I bought some Crayola Beginnings Tadoodles Crayon Buddies. We had a blast and here are the pictures to show her drawing. She overall preferred her left hand again, making us think she is a leftie like her Mimi.

Friday, February 01, 2008

Ben Stein on investing


Sorry I have been out all week, I have been in the City of Angels and my laptop crashed while out there. I don't have too much to talk about right now but I wanted to suggest that you all check out this article from Ben Stein on investing. Ben Stein has been an actor and lawyer and is considered an expert on politics and economics. I think he is a brilliant man who I'd love to learn more from, hence the reason when I saw this article I jumped on the chance to read it. Some interesting tidbits according to Ben:

  • Index Funds and ETFs are big winners
  • Investing 40% in international isn't unreasonable and is perhaps desirable
  • Stay away from Bond funds when you are young
  • Don't rebalance


Read the article for more details and his book, Yes You Can Supercharge Your Portfolio!, for even more info.

Here are more of Ben's writings and commentaries.

Monday, January 28, 2008

Our insurance company dillemma


Heather and I have been faithful Erie Insurance customers for years. How many years? I am at over 10 years and Heather is at over 12 years. Neither of us have ever shopped around for another insurance carrier. With Erie, I have been in 3 accidents, none my fault. They fought for me against the likes of State Farm, Nationwide, and Allstate who wanted to give me non manufacturer parts...and always won. Why is this important to me? First, the company stood up for me. Second, after market parts are not tested for safety regardless of what those insurance companies try to claim. How can you prove that the after market bumper will stand up to the same crashes that the manufacturer's will? Where is that data? It does not exist.

Well, now to my dilemma. Heather and I got a "survey" from Erie with a letter that led us to believe they wanted to find out information about our usage to ensure that they were not overcharging us. So, we both read it and talked about it before sending the survey in. We thought the company was trying to save us money and having been customers for over 10 years, we trusted that. Well, less than 2 weeks later we got a new bill and new policy information saying they used the information in our policy to change the classification of one of our vehicles and increase our yearly cost $70 effective immediately. It so happens that we have two cars, one worth half the other according to Wake County and the Blue Book value. The one that is worth half is now costing us about 15% more per year. Hmmm...

I am not sure how we were expected to take this change. The way we did take it however was a betrayal of trust as the survey said nothing about automatically increasing our policy and allowing them to make more money. The other part of our dilemma is that we have 3 policies with Erie. Do we change them all? Do we keep Erie because of the good experiences in the past? Checking rates, we can save money using other insurance companies. But, I have had such a good experience with Erie...is that worth the money?

I called our Insurance Agent that I initially had found through referral of my agent in Pittsburgh on Thursday and am still waiting to hear back from them. I have referred over half a dozen people to this insurance agency since being in NC. If I change agents, I feel like I need to tell everyone I referred to them about this to. Its not the agents fault...but an insurance agent can be pulled down by the insurance company they represent.

Sunday, January 27, 2008

Share your viewpoints


As I have been shopping for insurance companies which I'll blog about it later, I stumbled upon a cool site called Viewpoints. As one might guess, its a great consumer ratings site. I really liked the usability and readability of the site and became a member. The reviews were great, they even aggregate pros and cons at the top of each product page reviewed. This is one of those sites which can only be as good as the people participating, and they seem to have a lot of participation.

As for the insurance reviews, one of the few 5 star companies on their list was the company we currently use and have used for the past 10+ year...which increases my dilemma. More on that later. Until then, check out Viewpoints.com.

Saturday, January 26, 2008

Krispy Kreme Challenge


I read this blog posting and just had to share it. Over 3,000 people did the Krispy Kreme Challenge Run today in downtown Raleigh. This is a 4 mile run broken up in the middle with eating 12 donuts. Runners that lose the donuts on the 2 miles after eating 12 donuts are disqualified.

The most amazing thing to me is the fact that this took one guy, Philip Curley, just over 31 minutes to run two miles, eat 12 donuts, and run another two miles. Let's assume that he was running a 6 minute mile pace, he plowed 12 donuts down in about 7 minutes. I might be able to eat 12 donuts in 7 minutes before I can run 4 miles at a 6 minute mile pace :-)

Some race stats quoted from the blog posting:


2,400 calories
4 miles
12 donuts
1 hour
In order, those numbers refer to: number of calories eaten, distance ran, number of glazed donuts consumed, time alloted to complete the challenge. Some other key stats from the race:
31:20 — Winning time, registered by Philip Curley
10 — No. of runners for the first Krispy Kreme Challenge, in 2005.
3,035 — Number of registered runners for this year's race.
$20,000 — Money raised by the event for the North Carolina Children's Hospital
36,420 — Number of donuts prepared for the event
144 — No. of grams of fat in a dozen donuts (more than twice the recommended daily allowance)
2 — No. of minutes it took Dylan Selinger, a sophomore majoring in business at N.C. State to eat his 12 donuts
12 — No. of plastic lined trash cans awaiting runners at the finish line

Friday, January 25, 2008

Mortgage system problems -- real mortgage rates

I am one of many who believe the mortgage system is flawed. However, I think it is fundamentally flawed for a reason that is not often talked about. I think that root of the flaw is the abstract way mortgages are funded. What do I mean? I mean that most of the mortgages are backed by bonds sold by Fannie Mae or Freddie Mac. These bonds typically determine the interest rates. According to some articles, Freddie Mac and Fannie Mae account for providing the backing bonds for about 40% of the US housing market. Essentially, the lower the interest rate on these bonds sold, the lower the interest rate on the mortgages. If thats the case, why is there such a difference between the rates each lender shows?

1) Some lenders pay points (either through charging their customers or hiding them in fees) to lower the interest rate.
2) Some lenders are deceiving the public through the fine print. Who reads all 100 pages of mortgage documents when signing them anyway?
3) Some lender have higher rates to not deceive people but instead to make a profit themselves. If they have a slightly higher rate, they get more money.

But with all these different rates, how is a borrower supposed to know if he or she is getting a good deal or getting taken to the cleaners? One way they can know is to understand the system and look at the useful data provided by Freddie Mac. Freddie Mac provides a weekly survey of the actual average locked in mortgage rates and the points associated with those rates. If your mortgage rates being quoted don't fall close to this, read all the fine print. The farther they are away, the more chance that there is some funny business.

I guess I feel that the same way I did one year ago when I declared that lender laws need reworked. I feel that the mortgage broker should have the responsibility to do whats best for the client. This means they have to know what the client's financial goals are and what they can afford (maybe see a budget) before they offer up a mortgage for that client. If it didn't fit, they can be sued. Otherwise, how is the uninformed public who refuses to be informed going to not repeat our past mistakes.

Thursday, January 24, 2008

Establishing effective habits

The talk of the gym this week has been the fact that the gym was deserted...the New Year's Resolutionists were gone. One of the other guys at the gym suggested that the saddest thing was that many of them were so close to forming a true habit and that it takes 21 days to establish a habit. I thought that was interesting, only 21 days? That should help people survive a little longer. I found that 21 day claim on Google Answers.

This is useful information. Its useful if you are trying to get in the habit of exercising. Its useful if you are starting your journey to financial peace. But, this begs the question, if you know that something should be a habit 21 days later...do you get discouraged if its still difficult? I wonder..and with my new year's resolutions, I will try this out.

If you need to find some more habits to develop, I suggest the 7 Habits of Highly Effective People. Be Proactive, Begin with the End in mind, First Things First, Think Win Win, Seek First to Understand, Synergize, and Sharpen the Saw. I personally have never figured out how to Begin with the End in mind but put First things First. :-)

Two kids under the age of two?

Heather is entering her third trimester and even though Anna is growing up quickly, we will have two children 18 months apart. Every time I think this is going to be tough, Heather amazes me with how resilient, energetic and loving she is...even at 27 weeks pregnant. ;-) It it then I know that it is not that this will be difficult, but a fun adventure with the woman I love. Here is a picture of took of Heather putting Anna to bed last night.

Don't worry, I am not stuck in a euphoric state...I still think having two kids under the age of two is going to be a handful. But, Heather helps reaffirm that we can handle it. Also, everywhere we go and meet someone who has already been in that situation, they encourage us telling us that while its tough for a couple of years, its great afterwards. They tell us that the kids are best friends and they all live in some blissful. I am not counting on that...but I do hope our girls will be best friends. Beyond that, I am just holding on tight for the great adventure.

Wednesday, January 23, 2008

Refinancing

Heather and I have been considering refinancing our house but found that the fees of our current lender, HSBC were higher than we had though they would be ($2200). The first thing I did to see if refinancing made sense was to try the Bankrate.com refinancing calculator. Well, this calculator bases whether it makes sense on how much you would save on your monthly payment...not how much you pay monthly or when you will pay off you house and how much you will actually save. I thought this calculator was useful for someone planning to go to full term on their loan, but not someone that is looking to pay off the loan early. So, I had to go to Excel and adjust my amortization to change the rates, payment levels, and either have the new rate or the current rate plus $2200 paid immediately..plus calculate tax advantages of the different rates. What a pain, I may just have to write a web application to do this for people. In the end, $2200 paid immediately for us was a better fit rather than refinancing.

Tuesday, January 22, 2008

The Rice Pudding Dance

Tonight's installment of date nights with Daddy is about sharing desserts. Anna and I like to share snacks and desserts, and I am often more liberal with letting Anna try things like chocolate and ice cream than Heather...so we have fun. One thing Anna and I both like is rice pudding. I previously talked about the ice cream dance...well today I have a video of the rice pudding dance. The ice cream dance is slightly more excited than this...but this is exciting:


While I don't get quite as excited for rice pudding, my heart jumps in excitement for my little girl and those things which make her this happy :-)

Providence

I find the Gospel of Health and Wealth absolutely amazing. I understand that people want to believe that their situation is a direct result of their own actions, but completely ignoring other teachings in the bible to come up with this belief just seems odd to me. Look at Jesus's own life, he was beaten and crucified. Or Stephen, who was full of the Spirit and in sync with God when he was stoned. How does that align with Health and Wealth?

I think the most important thing that the H&W gospel have right is God's providence. That is, that God is sovereign over all events in our lives in history. One of the verses that the H&W Gospel hinges on is Romans 8:28. That is:

And we know that in all things God works for the good of those who love him, who have been called according to his purpose.

Does this mean that everything in your life has to be good for you? No! Look at Stephen, the best sermon preached by the new church was by Stephen in Acts 7 and he gets stoned for it. I have no doubt that this was for the good of all of God's people, but it doesn't mean that everything in life will be for your personal good. We can have faith in God's providence than we can know that any trials in our lives will be for the good of all of God's people. That's the heavenly perspective I am trying to ingrain in my life.

BTW, if you are looking for a great resource on the web for bible searching and studies, check out bible.crosswalk.com.

Movie Rentals....


Heather and I can be pretty frugal...but this entry isn't purely about the cost savings. See, we like to use Redbox to rent videos and watch them. This was an idea brewing for years but now is very very useful. We go to our neighborhood grocery store, Harris Teeter, which is about 1.5 miles away, and pick up the newer movie we want from a box slightly larger than a soda machine. It gets better, because we are able to make the decision which movie we want online and reserve it there..so we don't need to wonder if we can find something while in the store. Redbox charges us $1 + tax each day until we return it for a maximum of 20 times...after 20 days you own it. Its brilliant, and there rarely has been a time when i have thought my $1 was not well spent.

See, I have my own unique rating system. Its called, how much money would I have paid to see the movie in hindsight. Most movies I see come in at least $1..and with redbox I am paying $.50 per person...so I am always happy :-)

The sad thing is we can't see older movies or movies not on the mainstream. So, we do have to make the occasional trip to Blockbuster to pick up movies like Facing the Giants. But, thats probably twice a year max.

Monday, January 21, 2008

Anna's first airplane trip


Well, we just got back home from Anna's first trip on an airplane. Heather, Anna and I took a short trip up to see my sister in Connecticut. What I learned from this trip:

  • The time in the airport with Anna was the worst. We wanted her to run off some energy but she doesn't like to be told where she could go. I imagine this would make layovers particularly painful.

  • She did great in the airplane...and really likes fruit snacks and lollipops.

  • I have never been so happy to have 2 on-time flights. Great job American Airlines!

  • When possible, I will rent a car seat instead of traveling with one

  • It was smart not to rush off the plane. But, rushing on the plane wasn't a bad idea with limited overhead storage space on the little jet we were on.

  • Next time, I will were a shirt I don't care about becoming lollipop colored :-)

We have another airplane trip with her in 2 months...when heather will be 8 months pregnant. That will be interesting.

Thursday, January 17, 2008

Time to refinance?


What should be good news to the ailing mortgage industry is that the talk of the office today was whether or not to refinance their homes for those that bought houses in the past 2.5 yrs. Bankrate.com has the going rate at 5.42% and our current lender and bank, HSBC, had a rate posted of 5.50% earlier this year. For those that would be waiting for lower rates like me, I suggest you try the bankrate alerts where you can specify the rate you want alerted at.

TurboTax discount


I have been a user of TurboTax online for about 7 years now and I would highly recommend it. Here is a 25% discount for anyone to use, whether you have a Fidelity Account or not. If you work for IBM and are reading this, you will find we get a slightly better discount (30% off) though.

Project Baby Review

I have decided that we haven't done enough reviewing the various baby stuff we have bought and used over the first year of Anna's life. So, as we start to pull out and reuse things with our next little girl, I want to try to write a detailed review of those items. I will tag them in my blog under Project Baby Review. :-)

For now, here are some reviews Heather has written over time:

Health and Safety
Bath time including Fisher Price Aquarium Tub and Huggies disposable wash cloths
Diapers including Pampers Swaddlers and Pampers Baby-Dry
Bumbo Seat
Aquarium Color Change Shade
Swimming Float

Travel
Chicco Cortina Travel System Stroller and Infant Car Seat
Baby Bjorn
Jeep Overland Limited Jogging Stroller
Floppy Seat
Evenflo Titan 5

Sleep
Crib including Safety Lift Wedge

Food and breastfeeding
Lily Padz
Hooter Hider or Bebe au Lait
Enfamil Lipil Forumla
Avent Bottle Trainer Sippy Cup

Toys
Playskool Busy Basics Busy Ball Popper
Graco Baby Einstein Discover and Play Entertainer Exersaucer
Fisher Price Rain Forest Jumperoo
Playskool's Discovery Dome


Ok, so maybe Heather did a better job than I thought. :-) Here are the things we absolutely have loved from the above list...several other things we have liked, but are not so excited about it such that we would tell a friend they had to get one :-)

  • Fisher Price Aquarium Tub

  • Floppy Seat

  • Lily Padz

  • Hooter Hider

  • Graco Baby Einstein Discover and Play Entertainer

  • Playskool's Discovery Dome

  • Safety Lift Wedge


And here is what we haven't liked and why:
  • Aquarium Color Change Shade - It didn't work. We replaced it with a simple Eddie Power pull down suction cup shade

  • Jeep Overland Limited Jogging Stroller - It is not good for walking as it doesn't turn very well...others have front wheels that turn or lock. With the new baby, we are replacing it with a BOB Revolution

  • Evenflo Titan 5 - This may be the most difficult to adjust 5 point harness on the market. We quickly replaced it with a Britax Roundabout we like much better


I will try to make some further reviews with our second baby insight as we start pulling that stuff out.

Taxes, Withholdings and Deductions

First, I should remind everyone that now is the best time to redo your withholdings on your W4. The best place to do this is the IRS Withholding Calculator. By recalculating your withholdings annually, you will help ensure that you are not giving the government an interest free loan AND that you will not owe money at the end of the year. If you are getting married or having a child this year, it counts for the entire year...so calculate it as such.

That said, there are some new rules in the IRS this year which have caused us a bit of a headache. Defined in IRS publication 526 for 2007, there are new rules about deductions and in particular what documentation must be needed. For cash contributions of any amount, you must have one of the following regardless of the amount you contribute:


1. A bank record that shows the name of the qualified
organization, the date of the contribution, and the
amount of the contribution. Bank records may include:
1. A canceled check,
2. A bank or credit union statement, or
3. A credit card statement.
2. A receipt (or a letter or other written
communication) from the qualified organization
showing the name of the organization, the date of the
contribution, and the amount of the contribution.
3. The payroll deduction records described next.

Since our bank doesn't make available to us our cancelled checks, we are stuck in limbo hoping the charities give us a receipt or we will have to figure out the check numbers and request them of the bank.

But the new rules don't stop there, they take special exception to any single contribution over $250. If you have five $50 contributions, that wouldn't count. But, a single $250 contribution has special rules. The rules are that the charity that you gave this $250 or more donation to must acknowledge that contribution and the acknowledgment must meet these tests:

1. It must be written.
2. It must include:
1. The amount of cash you contributed,
2. Whether the qualified organization gave you
any goods or services as a result of your
contribution (other than certain token items
and membership benefits),
3. A description and good faith estimate of the
value of any goods or services described in (b)
(other than intangible religious benefits), and
4. A statement that the only benefit you received
was an intangible religious benefit, if that was
the case. The acknowledgment does not need to
describe or estimate the value of an intangible
religious benefit. An intangible religious benefit
is a benefit that generally is not sold in
commercial transactions outside a donative (gift)
context. An example is admission to a religious
ceremony.
3. You must get it on or before the earlier of:
1. The date you file your return for the year you
make the contribution, or
2. The due date, including extensions, for filing
the return.

Overall, this makes it tougher on those of us who are contribute to various charities. In a given year, thanks to many queries for support, Heather and I may give to 15-20 charities. Now, we have to try to track down receipts, canceled checks, and acknowledgments for all of these contributions. Some contributions may be as low as $5-10. So, at some points I guess the government wins because people may not go through the hassle for deducting those small contributions.

Wednesday, January 16, 2008

New Year - New Blog

I am really trying harder to blog this New Year. And with that, I decided that I will try to make better use of the labels available...I even added the label bar off to the right. Let's see if I can keep it all straight :-)

The ice cream dance

Yesterday, we gave Anna ice cream for the second time...just so happens to be the second time in a week as well. We were at Jason's Deli celebrating our good friend Suzanne's birthday. For those not familiar with Jason's deli, they have a free soft serve ice cream machine. So, I got Anna a little bit of vanilla/chocolate twist in a bowl. As with all things, she took a very small taste first to see if she liked it. As with most things (I think she likes over 90% of what we give her), she loved it. But, she loved it more than most, so much that she felt the need to dance in her high chair. In between every bite of ice cream, she did a little dance. It was adorable.

A special shout out to The Twisted Fork where Anna had her first vanilla ice cream. Their kid's meal was a great deal with offering dessert instead of a drink and for a very good price. This is great because we normally bring Anna milk and either drink her drink or don't get it at all. We got an ice cream cookie sandwich, which gave both Heather and I a cookie with some ice cream on top and Anna her first taste of ice cream. I can't recall her doing the ice cream dance there though...which will be in my mind as pure happiness for a while.

Tuesday, January 15, 2008

Tithing time

One of the key phrases that our pastors at Crossroads Fellowship here in Raleigh like to say is to "tithe your time, talents and treasures." I have been thinking about that a lot lately. It took me many years, but I am confident that we have the treasures pretty well understood. But, talents and time?


Let's think about time in a week. 24 hours a day, 7 days a week, and what is one-tenth of that? 16 hours and 48 minutes in a week. Woh! Maybe on the monthly level it would be better. One-tenth of 24 hours for 30 days? 72 hours! 3 days! Let's see, in a good month I can count an 8 hour day at Habitat, four small groups at 2 hours a piece...--struggling--...6 hours at church...maybe 30 minutes a day so thats another 15 hours. Totaling: 37 hours.

Well, now that I have another New Year's resolution to work on...

Monday, January 14, 2008

Pregnancy confirms my Pro-life stance

I have heard a lot of arguments over the past about the fact that I am a male especially means I don't have the right to tell a woman what to do with her body. And, I have never tried to disagree with those...but words my wife spoke last night have been echoing in my mind as the glaring reason to be pro-life when taking religion out of it. Here is roughly how the conversation went with my wife, Heather, who is 25 weeks pregnant:


Heather: -- painful sigh --
Erik: What's wrong?
Heather: Just the baby kicking.
Erik: Does it hurt?
Heather: It often doesn't hurt, but its just very unexpected. Not being able to prepare for the kick always causes a little reaction.

This conversation reminds me that the unborn baby has its own brain and moves itself. The woman is not able to control the baby like she can the rest of her body. Our baby girl is 25 weeks old...still the age that abortions are legal. But, from Heather's statements like this one, the baby obviously has a mind of its own. When we saw her on an ultrasound at 8 weeks, she was moving on her own and had a heartbeat that is unique from Heathers. She had her own body parts, heart, and movements.

I think having gone through the father side of now Heather's second pregnancy continually reiterates my belief that the unborn baby is a unique creation from God and it is our responsibility to protect him or her. I am not trying to tell the woman what to do with her body, but protecting the unborn baby's life. My religious beliefs further reiterate the sanctity of life.

Sunday, January 13, 2008

The envelope system - Mvelopes.com


As I was reading through this Sunday's New and Observer, I stumbled upon a reference to Mvelopes in the Wall Street Journal Sunday section by Amy Hoak under an article entitled "Web Sites to Keep You on Budget." Interestingly enough, this is the method Heather and I were featured in the New and Observer for using. Amazingly enough, most of my colleagues and friends had no clue what the envelope system was and I heard more jokes than anything. In fact, my cube walls were covered in envelopes when I returned to work.
Envelopes as cube wallpaper
But, Amy in her article this morning didn't feel the need to expand on what the envelope system was...so I think it must be fairly cut and dry. She said, "[Mvelopes.com] is based on the envelope method of budgeting, which allocated funds by expense category."

Heather and I use Mvelopes and really enjoy it. We found it off of the Crown Ministries website. I think they have a one month trial, but its quite amazing. Even if, like Heather and I, you use a Credit Card for most of your purchases (hopefully with cash back or rewards)...you can easily allocate those expenses to the individual envelopes. I highly recommend checking it out.

Friday, January 11, 2008

I guess my candidate is...

Following other family bloggers lead, I tried this Candidate Calculator. Its a useful tool for people who don't have time to weed through each candidates position, which normally is made clear in a 14 page essay! At the bottom I left it Undecided so that it would not take my current preferences into account on anything but the issues. Here are my results:


Mike Huckabee - 74.00% match

Your Other Top Matches
California Representative Duncan Hunter (R) - 68.00%
Businessman John Cox (R) - 67.00%
Colorado Representative Tom Tancredo (R) - 66.00%

Middle of the Pack
Former Massachusetts Governor Mitt Romney (R) - 61.00%
Arizona Senator John McCain (R) - 60.00%
Kansas Senator Sam Brownback (R) - 56.00%
Delaware Senator Joseph Biden (D) - 55.00%
New York Senator Hillary Clinton (D) - 54.00%
Former North Carolina Senator John Edwards (D) - 54.00%
Illinois Senator Barack Obama (D) - 53.00%
Connecticut Senator Christopher Dodd (D) - 52.00%
Ohio Representative Dennis Kucinich (D) - 50.00%
Former New York City Mayor Rudy Giuliani (R) - 49.00%

Bottom of the Barrel
Former Alaska Senator Mike Gravel (D) - 47.00%
Former Tennessee Senator Fred Thompson (R) - 44.00%
New Mexico Governor Bill Richardson (D) - 41.00%
Texas Representative Ron Paul (R) - 33.00%


Party Results Republican - 53.24%
Democrat - 46.76%

I think the most amazing things to me were
1. 46.76% Democrat? Wow..I never have sided with a democrat in my 10 years of voting.
2. How low Giuliani, Thompson, and Paul were? 33% with Paul? thats crazy!

Wednesday, January 09, 2008

Working out? Whats your motivation?

In the packed gym (but numbers are already dwindling) this morning I overheard a conversation that really got me thinking...thinking enough to blog about it. The conversation went something like this:
Really Muscular Guy: "Good to see you at the gym this morning"
Groggy slightly overweight guy: "Yea"
Really Muscular Guy: "Whats your motivation?"
Groggy slightly overweight guy: "To lose weight"

So, this was at the start of my workout, about 5:45 AM. I had the rest of the workout, the time getting ready for work, and the commute into work to think about this question...about another 2 hours. You hear a lot that losing weight is the most popular New Year's resolution...to drop. So, why is that?

Judging from my personal experience over the past 5 years, I think the problem is one of motivation. If you goal is to lose weight, what happens when you have done that? Or what happens when you hit that first wall. Anyone could watch the Biggest Loser and tell you that everyone, even with personal trainers, will hit walls when trying to lose weight. If that is your only goal, I think you can plan on having that goal pop up on your radar every couple years for the rest of your life.

In my own personal life, I have jumped on and off the workout wagon about 6 times in the past 5 yrs. On my current track, I have been going at 5:30 AM every morning for the past 4 months. Its probably the second longest streak in my short life, the longest was solidly from April 2001 to about January 2002. I stopped after that 1.5 years because more of my time was being spent with my then bride-to-be and I wanted to keep her as number one in my life. Plus, with everything I had going on, it was the lowest priority and I guess I just no longer had the motivation.

I started up from time to time with the motivation of losing weight or getting in shape, with no real goals. Those typically failed from the start as I failed to establish a routine. When my daughter was born in October of 2006, I started to again thought about working out but couldn't fit it in the weekdays as I didn't want to lose what precious time I had with her. I mean, she is awake from 8 AM to 1 PM and 3 PM to 8 PM roughly...that means I only get about 5-8 PM with her if I am lucky and then the rest of the night with my wife!

But, this fall I found new motivation. I realized that the lifestyle I wanted for my new growing family was a lifestyle of fun activity. I didn't want to risk getting into a position where I was too out of shape to go hiking, rock climbing, kayaking, or biking with my family. I want my family to be a family of adventure and a family of activity, not one that watches a TV show together but one that explores God's great creation with one another. I want to be as healthy as possible so in the years I have with them, we can do these things with one another. There is my motivation, its all I need. I don't care what weight I am, I just want to be in shape to experience life with my family to the extreme. I don't want to be the man on the couch, I want to be this man:
Erik hiking with Anna on his back

Over this Christmas vacation I had, we were blessed to have my mother here for a bit. Together, we looked through thousands of pictures my father had scanned from slide format. With long time friends of my parents over one day after Christmas, we showed them some of the old pictures. They commented about how our family was the family always at parks, camping and hiking. I have many fond memories of camping with my family. Here are some from when I was 5 months old and my sister 4 yrs old...
Erik on his mom's back hiking at about 5 months old
Erik on his dad's back hiking at about 5 months old

I am motivated to have the same for my family. I want to be in the physical condition such that my children can experience that. There is my motivation for the new year.

Saturday, January 05, 2008

Big shoes to fill

Anna is growing up quicker than I ever imagined could happen. Let's try to name some milestones...

  • The other night, she got her blankey and told Mommy that she was ready for bed
  • She climbs with ease up and down the stairs
  • She has a new room that looks older and more mature
Anna in new crib
  • She eats most everything we eat and eats out of things like raisin boxes with ease
  • She is starting to understand a lot more, we taught her things with ease like what a belly button is

Thankfully, tonight she did something that made me remember just how young she is...
Anna in Daddy's shoes

Friday, January 04, 2008

Sony DCR-HC28 review

I am a novice video guy, this is my first video camera. But, having a 1 yr old daughter and another on the way had me wanting a video camera. With some Best Buy gift cards given to us for Christmas, we decided it was a good time to take the plunge.

The Good

  • Very inexpensive. It was $225 on sale at Best Buy.
  • MiniDV is uncompressed and therefore pretty easy to edit.
  • Firewire to our Macbook is very fast and easy to use with iMovie.
  • Very Small and lightweight.
  • Image stabilization seems to work pretty well
  • Everything bad I read was about the sound, but I find it to be very clear.
  • It does a good job of managing different mini-clips in the playback system. Not sure what this is called, but it automatically resets the counter to 0:00 after each time we pull off the movie clips. this could be standard, but is really a nice feature.
  • Battery life seems to be great for what we use it for, a bunch of small 5 minute clips.
The Bad
  • No 16:9 mode...which all my TVs are widescreens.
  • On our MacBook and large LCD TV, these videos really start look amateur in full screen. Look fine on a youtube like interface.
  • Why is it the 4 pin firewire instead of 6 pin?
  • Firewire cable is expensive, ~ $30
  • Touchscreen controls are not that easy to use for me. My wife seems to hit the buttons with more easy.
  • Its very difficult to keep the camera steady at 20X zoom. Not sure I would ever use it or anything higher unless I bought a tripod.
  • The default zoom level seems to be too close. you can't take videos unless you can step back a good bit.
  • Using the tapes as storage is a bit kludgey in terms of rewind, play, etc.
The best thing about our camcorder is iMovie. So, its not so much the camcorder as the software which didn't come with the Sony but with our Macbook.

Overall, I might buy an HD version using flash memory if I were to do it again. That is, for small 5 minute clips to capture moments.

Sunday, December 23, 2007

Have a Merry Unsantatized Christmas

Our singles / college pastor, Bryan Finley, did our Christmas service today at our church. Eventually, you should be able to hear it here. It was a great sermon and talked about how many of our rituals and traditions have us sanitizing Christmas to become something other than what it is about. When he said sanitizing, I at first thought he said "Santa-tizing" thanks to that wonderful southern accent I am still getting used to. Santa-tizing is also a very applicable word, since its making Christmas about Santa and gifts instead of about the birth of our Lord and Savior Jesus Christ. Santa-tizing is exactly what happened in Vegie Tales movie entitled "The Toy that Saved Christmas." But, its far worse than just making Christmas about gifts or even giving, but making Christmas about families and as Bryan quoted one radio host, "Christmas is what makes our nation great." Christmas is not any of that, but about what makes our God great. He came into this world humbly and humbly offered Himself to all of us. And we celebrate Christmas as the day He came to earth for us.

So, I say have a Merry unsanitized and unsantatized Christmas!

Sunday, December 16, 2007

Timeshares

Heather, Anna, and I just got back from visiting with my father and step-mom at Myrtle Beach, staying at the South Beach Resort at Myrtle Beach. My father used RCI to trade in some of his timeshare to go to another. Here Heather, Anna, and I are at the South Beach Resort:

This past trip, combined with memories from my last Myrtle Beach trip, had me thinking about timeshares. Two years ago Heather and I went to Myrtle Beach with our close friends Aaron and Suzanne in December. We had decided to go to the Dixie Stampede for their Christmas show. (Very good show incidentally. Everywhere in Myrtle Beach seems geared to sell you a timeshare, from Malls to restaurants, and unfortunately Dixie Stampede was not different. We were offered a free drink and appetizer during the preshow for filling out an information card. It wasn't surprising to us that Heather and I, being young DINKs (dual income no kids), hit their target market for anything they wanted to sell us. Well, they offered us a couple hundred dollars and breakfast if we spent a couple of hours the next day at the Sheraton Broadway Plantation timeshares. We didn't have any plans, so we said sure its worth a couple hundred dollars to us to check it out. So, we took the tour and enjoyed the place. Since I was familiar with Hilton Grand Vacation Club, I knew much of what this was all about. We enjoyed it and seriously liked the place. A 2 bedroom unit at the time would cost $18,000 and also need $750 maintenance per year. To Heather and I, that is not something we can make a quick decision on, and things then started to get bad.

The sales guy who was previously very nice to us, turned very rude when we said we were not interested in making a decision that day. Apparently, he thought we really were wasting his time. He badgered us a bit and we told him we definitely were not going to buy. Another person came over who we complained to (complaints on deaf ears) and we walked away with our couple hundred dollars, but very angry.

Since then, we have had other offers for free weekends or other things if we sit through timeshare pitches. I think that the experience was so bad, unless we were really interested we would never do it.

Incidentally, I loved the Starwood Vacation Ownership, even though I don't think I could ever buy into it because of that sales guy. I think Heather and I will just scrimp and save and hope we someday can buy a lakehouse. We may be turned off from timeshares forever...but we can still enjoy our parents like we did this weekend :-)


We liked the South Beach Resort, things seemed in good repair although the amenities were the bare minimum. They had cheap linens and an unimpressive workout facility and lazy "river" as well as some poor customer service. Maybe I will blog another day about the problems with many of these places as I have been to enough. Starwood solves many of these problems, too bad that bad taste will never get out of my mouth!

Thursday, December 13, 2007

Brrrrr... It worked

To follow up from my last story, about the tramatic night Anna and I had with her big ouchy. She woke up the next morning with no mark and no bruise. I guess the ice worked! Or maybe I overreacted. Let's just say the ice worked!

Here is Anna from yesterday night with her pink Harris Teeter baloon and playing with her favorite toy, Cassie...


It was so warm yesterday (in the 80s) that she was bare-legged. It had been so long that she didn't have on tights or pants on, her legs were extremely ticklish. That made for a fun night because every time I grabbed her she would giggle.

Tuesday, December 11, 2007

The Big Ouchy

Tonight something happened that never happened on my guard alone, Anna fell and had a big ouchy. It started with her really enjoying her big pink chair. Mommy had sat on it with her before she left, and she continued to play with the chair.

Eventually, she start moving the chair. She moved it in the middle of the floor, pure hardwoods and no rug. Well she stood and leaned on the back as she had done many times, but this time it didn't hold her. She did a face-plant on the hardwoods having tipped the big pink chair over.

Typically when something tragic like this had happened when it was Heather and I, I'd call in the calvary. Heather and I would double team her with love and all would be well. Well, Daddy didn't do too bad himself. I wisked Anna away and changed her perspectives, went to a different room altogether to get her thinking about something else. We went upstairs and read a book. All was well, the tears had stopped and Daddy's little girl just got more cuddly.

However, the trama was not over. I noticed Anna got a big red spot. And not wanting Anna to end up with a big black and blue mark from one of her few times with Daddy alone, I decided to ice it. Well, this was worse than getting hurt to begin with. After 10 minutes of holding ice on my little girl's head and her crying the whole time, I let her go and prayed that she didn't get a big bruise. All that crying wore her out, and she was acting pretty sleepy early...leaving me to write this blog entry ;-)

Tuesday, December 04, 2007

Dad alone? Play with the baby!

As I wrote last week, Anna and I have been having Tuesday night date nights. Two of the nights I went out shopping with Anna and noticed that as I walked around with Anna people tended to come up close to Anna more so than normal. Is a Dad all alone a reason to approach the baby? When Heather and I are out, Anna gets comments but not approached and touched. When its just me, people have a tendency to get close to Anna and do things like grab her feet. This seems really odd to me, and I don't think this happens to Heather when she is alone.

Sunday, December 02, 2007

Merry Christmas Lights!

We aren't the types to spend too much time on the Christmas lights, but I put up the decor of the year outside. This year we went with icicles in addition to our normal lights on the big evergreens, garland and bows on the posts, wreath on the door, and the candles in the window. Here is a picture of our house:

New rooms

Much of this weekend has been spent redoing two of our bedrooms for new usage. Prior to this weekend, we had a nursery, office, and guest bedroom beyond our master bedroom. With another sweet baby girl on the way, we decided to reorganize into a nursery, Anna's room, and a guest bedroom/office combo. So, my mother-in-law and I spent Friday afternoon and Saturday morning painting the two rooms and Saturday afternoon rearranging furniture. My mother-in-law is the real skill when it comes to painting, no tape needed...so I just do the rolling and she does all the edging. We painted Anna's room a green to match her new linens, Banana Fish Bubble Gum. Anna seemed to love her room!


The guest room/office was a dark green on the blueish side...it is now more of a warm milk chocolate or mocha.


Still have to hang art and curtains, but you get the picture :-)

Friday, November 30, 2007

Its a girl

My date nights have helped prepare me and get me excited for the arrival of another sweet little girl. Heather, Anna, and I went to the doctor's today for an ultrasound. We found out that everything seems normal and healthy, a huge blessing, and that they confirmed that Heather is almost 19 weeks pregnant,. The due date by the ultrasound was April 27. Anna was 5 days early, if the new baby girl is also 5 days early Mommy and the her may share a birthday!!

The tough part now is that we had a boy name picked out as a carryover from when Anna was around. We had much more trouble with girl's names the first time. Let's see if we can do better this time.

Wednesday, November 28, 2007

Date nights with Anna

Anna is now 13 months and Daddy and her have date nights when Mommy has plans. Last night was one of those nights, and we decided just to stay in and play. Anna was really busy last night, spending 5-10 minutes on each task before moving on to the next task. They were important things like playing with special toys, pushing around her shopping cart, or pulling all of the DVDs our of the cabinet and putting them back.
Anna with a DVD
I can't forget Anna's favorite playtoy, Cassie. She loves everything about Cassie. Cassie makes her laugh without even doing anything. Cassie also takes a lot of abuse and doesn't even snap at Anna in return. Cassie goes crazy when we have guests over, but she really is an angel around Anna and we couldn't be happier with how she is with kids.
Anna with Cassie
Anna kissing Cassie

Our Year of Maintenance

2007 will thus be deemed in the Burckart household, the year of maintenance. Not anything to do with our daughter or the conception of our next child...but the year of maintenance. Coincidental that our house was built 10 years ago in 1997? I think not. Here is what we have had to do in the past year:
1) Change the torsion spring in the garage door.
2) Replace the boots around the plumbing vents on the roof
3) Replace the mailbox
4) Replace the upstairs AC unit and coil
5) Replace the water heater
6) Replace the cabinets, counters, appliances, floors AND subfloors because the dishwasher leaked and caused the subflooring to rot, mold, and buckle underneath the cabinets into the breakfast nook and throughout the kitchen.

And today, the furnace stopped working upstairs. Not to mention that a friend of ours has told us that our downstairs AC unit/gas pack unit is going and will need replaced next year. Incidentally, in July before #4 and #5 happened, I looked up this article from USA Today about when things will go bad and what preventive maintenance needs done. Here are some things that jump out at me:

  • Water heater expectancy: 15-18 yrs
  • AC units: 15 years
  • furnaces: 20-25 years

You'll notice that we are 5-10 years ahead of schedule for things falling apart. That is why this year is the year of maintenance.

**updated because I forgot about the most expensive kitchen expense :-(

Sunday, October 07, 2007

Cool website: Zillow.com


I was checking out this website, Zillow.com, and it is by far the coolest new power tool I have seen in a long time. It shows you all those things previously unavailable to the common purchaser without going through a real estate agent, estimate values of homes, "Make Me Move" prices, recent sales, and houses for sale on a Google Map like easy to use interface. I am amazed...great job Zillow!

Tuesday, August 14, 2007

For me, Blackberry 8830 wins out over iPhone

I recently made a tough (for me) decision as to buy the cool, slick, Apple iPhone on AT&T or the new but not as cool Blackberry 8830 on Sprint PCS. I have heard from many friends as well as people I trust online such as Jeff Pulver about how great the iPhone is...but I wasn't sure it made sense for me. In the end, I bought a BB 8830...here is why. First, I compared feature sets taking into account the networks:


featureiPhoneBB 8830
Phone accessX
Email accessX
Maps / Yellow pagesX
News readingX
Web BrowsingX
Worldwide usageX
Message typabilityX
Multimedia accessX
PriceX
Cool intangiblesX


In the end, I made the following decisions:
  • I will mainly use mobile wireless access for email, maps/yellow pages, and news reading and do not need a general web browser. Email (push + speed), Google Maps (GPS + speed) and News (speed) are all better on Sprint PCS. Google maps with GPS is just a better experience. Likewise, reading news at EVDO speeds on Sprint just can't compare.
  • I need a device I can drop a foreign GSM SIM into..something traditionally good with AT&T and bad for Sprint but not for these devices.
  • I don't think we have advanced enough in battery technology for an iPhone to take place of two devices...and it doesn't have a hard drive or work with my docking station like my 80GB Video iPod.
  • The tactile feedback on the BB was easier to type for me with big fingers than the iPhone. If I am going to use it for email, typability is pretty important.

Finally, I couldn't buy the iPhone on cool intangibles alone..and I am really happy with my BB 8830.

Now, I will be prepared to be slammed by my friends and unknown Apple followers on the internet for saying I liked something better than an Apple device. But, I thought I would, at very least, offer my evaluation so some person may gain.

Ohh, and the price thing is corporate discounts on service aren't applicable if you have an iPhone. I like my heavily discounted Sprint service.

Sunday, August 12, 2007

Weekend with Anna

So, today is my last day alone with Anna while Heather is having fun with her cousins and aunts in New York City. Anna has been an angel, she slept til 7 on Friday and Saturday and 8:30 today. The activities have centered around constant motion. She has crawled everywhere, walked with her walker everywhere, and chased the puppy everywhere :-). Friday and Saturday she slept for 2 full hours each morning and afternoon. She is waking up now, which means she will have only an hour nap this morning.


Unfortunately, Anna's morning schedule this morning did not lend itself to me getting to church. By the time I changed, bottle fed, changed, and fed her solids...it was already too late for me to get to church for the 9:30 and she was sleepy around 10:15 which meant no making the 11 AM.

I did make it out of the house twice this weekend. The first time we went to Suzanne and Aaron's to celebrate Aaron's 28th birthday. It was fun, but a bit late for Anna. We started dinner around 7:20 PM and I didn't get home til 9 PM after semi-rudely running out. Thats about an hour after Anna's bedtime. We also went with Uncle John to the farmer's market and ate at the great seafood restaurant. We met Mike and Jenn there and had a good time. We also bought a couple boxes of tomatoes so Uncle John can make us sauce.

Anna was great. If only Cassie would learn from her. Cassie has been trying her best to demand my attention. She has gone potty on the floor 6 times, carpet everytime. Last night 3 times even after waking me up at 12:30 AM and 2 AM to take her downstairs to go potty. Next time, I may have to board her.

Friday, August 10, 2007

LG appliances

Heather and I recently redid our entire kitchen. We are not huge fans of the stainless steel appliances, so our choices in colors were limited from there. We felt we either had white, traditional black, or high gloss black. We decided to go with the high gloss black. After a lot of staring at the different brands, we took LG because their price, function, and style best suited our desires.

So, we have now had our LG appliances all fully installed for 4 months. A french door refrigerator with ice on the door (LFX25960), a range complete with convection and 4 burners and a warmer on the cooktop (LRE30451), a microwave which is substantially styled different ( LMVM2075), and a not fully integrated dishwasher (LDS5811).


This morning, the appliance repair man comes to our house for the second time in those four months. The first time, the dishwasher was leaking on some cycles it was running...it wasn't locking and sealing shut. The very good appliance guy quickly replaced the mother board like thing and its worked perfectly since. This was a big scare since one of the remodeling reasons was the dishwasher, which leaked and ruined our kitchen and dining room subflooring.

This time, the refrigerator periodically freezes up when using the dispenser. It works otherwise, but until it resets itself in 5 minutes or so, all you can get is water out of the dispenser. So, we are two out of our four brand new LG appliances have had some problems. However, our experience with the first repair was so good, I wouldn't not buy them again. We'll see if thats the case after this repair where we have something we can't repeat on demand.

Incidentally, we did buy all the appliances at Home Depot and have the extended warranties on everything but the microwave. Their extended warranty is a flat fee ($60 for 1 yr and $90 for 3 yr I believe), and after all the discounts we paid less than $300 for the microwave...it was odd to think about paying 20% of that for an extended warranty.

Back to blogging..

I know I have missed blogging for quite some time...but I am going to make another effort. No promises. :-)

Monday, May 07, 2007

Saving, Budgeting, and Marriage...

Heather and I were interviewed by Sue Stock from the N&O, our local newspaper here in Raleigh NC, about how we manage money as a fairly young married couple. The article is here at the N&O including a picture of us with our daughter Anna under More Photos on the right. The experience was great, Sue was nice as well as the photographer, Chris Seward, who spent 45 minutes at our house ot get some various photos of us.

Most of the interview we talked about our system of budgeting, called the envelope system. We didn't develop this system but were taught it by people related to the Crown Financial Ministries organization. Our church, Crossroads Fellowship, teaches part of the Crown curriculum as well as information from other popular financial freedom ministries and personalities like Dave Ramsey. As part of enforcing our envelope system, which I will describe in more detail in a second, we use Crown's Money Matters software which they now call Money Map software. They also have an online budgeting software package called Mvelopes which also budgets with an envelope system.

The first key concept in our system comes down to the order in which you handle your money. When we first receive money, Heather divides it into the envelopes immediately. First, we give back to God a portion of the income He has blessed us with in our tithes. Next, we save a portion of our income in a variety of ways, general savings, emergency savings, college savings, college investments, new car savings, general investments, and other such categories. This keeps savings as a priority in our lives and moves the money away from where we are likely to spend it on a whim. Next, the money gets allocated to the various other account "envelopes" we have. This includes things like our utility bills which can be static or dynamic as well as our grocery and gasoline envelopes which we can use throughout the month. There are other envelopes that gather money to be spent later in the year, like travel envelopes, gift envelopes, or our personal envelopes which Heather and I can use personally at our own discretion.

When the month is over, some envelopes may still have a balance and others may not. Things like our grocery and electric bill envelope both often may have balances. However, whereas the grocery bill envelope probably doesn't need a month to month balance carryover, the electric bill does so that there is more money available in a hot summer. The leftover money in the grocery bill may be carried over to spend on a fancy meal the next month or be pushed into general savings for usage elsewhere as needed.

Overall, this system has worked nicely for us. But, a budget system alone doesn't help people stay on budget. It also requires discipline which is the personal struggle for me. Heather is very disciplined but I am not. So, one of the useful tricks which is available with the envelope system is to not make it virtual in the areas where you are having problems staying on budget. For example, if you cannot stay on track with eating out because it just goes on your credit card, we would suggest you move to cash in an envelope to pay for all of your eating out. Its easy to tell if you have enough money when you just have cash in an envelope.

Thats all for now...I may write some more later...

Thursday, March 22, 2007

Oh, the taxes you'll pay

Here is a great article from Steve Forbes reminding me why I voted for him in past presidential primaries. Check out this quote:

If you drive to work, you pay gasoline taxes and maybe a toll or two. You already paid fees on your license and registration, not to mention the sales tax when you bought the car, along with transfer fees and various add-ons devised by your local pols.

Then there's work. Politicians take gargantuan bites out of your pay: federal income taxes, state income taxes, Social Security taxes, Medicare taxes and, perhaps, local income taxes.

Anything you buy during the day has also been subjected to taxes. This doesn't mean that you pay all of them directly. When you buy, say, a new sweater, you're paying countless disguised taxes. These include the taxes that companies pay on their profits, along with workers' Social Security taxes, property taxes, utility taxes, corporate excise taxes, among others--all passed along to you in the form of higher prices.

But wait, your day isn't over. You return home--after more of those gas levies and tolls--and you go through the mail. Uh-oh. Your county or township has sent your property taxes. Have a pet? Probably time to renew the license on Fido.
Its amazing to think about...everything we do we end up paying taxes on. Even "tax free" purchases, we end up paying taxes on because the businesses we buy from pay taxes, pay social security for their employees, etc. Its amazing and horrible all at the same time.

Here is a great paragraph from Steve:
The inconvenient truth that politicians and others ignore is that taxes not only are a way for the government to raise revenue but are also a price and a burden. The tax you pay on income is the price you pay for working; the tax you pay on profit is the price you pay for being successful; the tax you pay on capital gains is the price you pay for taking risks that pan out. The principle is simple: If you lower the price and burden on good things, such as success, productive work and risk taking, you'll get more of them; raise the price, you'll get less.

And, finally, he points out the federal tax code is a burden on the citizens of the country.
"Abraham Lincoln's Gettysburg Address, which defined the character of the nation, is all of 268 words. The Declaration of Independence runs about 1,300 words. The Constitution, which has served us for more than two centuries, comes to some 5,000 words. The Holy Bible has 773,000 words. The federal income tax code and all of its attendant rules and regulations: 9 million words and rising. An appalling fact about the tax code is that no one really knows what's in it."
Brilliant. Thanks Steve for being honest and pointing out what escapes us in our day to day lives.

Friday, February 23, 2007

Induction cooktop or not

We are making plans to potentially refinish our kitchen. This means new cabinets (and a slightly different footprint), new countertops, new sink, and new appliances. We are pretty solid on the color/company of cabinets with Thomasville Cherry Brierwood and are also set on Quartz countertops although perhaps not yet set on the color. The sink is not a pretty exciting decision, but the appliances are...

I have a tendency to want to stay away from GE and Kenmore appliances...because they are fairly commonplace. But, I decided the first thing I would discover are which features I would like in each appliance. Most were pretty simple, but ranges have been giving me the toughest time.

The hottest topic of debate in my mind today is induction vs a regular smoothtop cooktop. Induction cooktops are the latest technology which uses electromagnetic energy to heat the pan while maintaining a cooler cooktop. Many popular things like electronic toothbrushed use induction to charge. The only thing heating a cooktop of an induction cooktop is the pan which has been heated. This means the cooktop doesn't get to "burn your hand" hot and kids are safer. But its expensive...add another $1500 compared to the cost of a freestanding range to get an induction cooktop AND a under counter convection oven. So, $2500 vs $1000...thats a pretty big deal. It uses less energy and won't burn someone.

If you told me today Anna would be burned by a smoothtop model..I would by the induction based cooktop in a heartbeat. But. since you don't hear of it happening too often, I am not sure I should worry about it. I wish I had statistics as to how many kids get burned by smoothtop models.

Sunday, February 18, 2007

Brand names or products

Heather and I were considering how brand names infiltrate our lives...here are some brand names we use, even if we aren't using the brand in question...

Kleenex
Band-Aid
Q-tip
Saran wrap
Vaseline
Walkman

Modern day brands still coming up:
Google
iPod
Tivo

Other possibilities:
Coke
Pergo (I have noticed people use this for any fake hardwood flooring)

How did this start? We opened a new thing of Saran brand saran wrap and noticed it worked better than the knock off brands and we usually call the knock off brands Saran wrap...but they don't deserve that title :-)

Anyone have others?

Saturday, February 17, 2007

My daughter..

I have yet to post the reason for my 4 month leave of absence from blogging or pictures of the beautiful girl who stole my heart. i think its about time to toss a couple of pictures out here.

This is the latest, from Thursday Feb 15:
Play Time in the Exersaucer


And from the day before for Valentine's day:
Happy Valentine's Day

Friday, February 16, 2007

Savings rate gets worse...

Sadly, the poor savings rate of the US public, a negative 0.4% in 2005, got even worse in 2006. It is now 1% according to the Commerce Department. The savings rate is typically, as I understand it, the amount of after tax income that people save. So, it being negative means the average person in the US is spending 1% more than their after tax income!

Here is an article on it. Here are some quotes from the AP article:

"[T]he Commerce Department reported Thursday that the nation’s personal savings rate for all of 2006 was a negative 1 percent, the worst showing in 73 years."

"The 1 percent negative savings rate in 2006 followed a 0.4 percent negative rate in 2005. There have been only four years in history that the savings rate has fallen into negative territory. The other two were 1932 and 1933 during the Great Depression."

Its funny, I don't remember seeing this make the headlines I would expect. This is a pretty serious problem....and sadly its our children who will pay for it.

Lending laws..more...

Wow, I missed this link in the mortgage nanny article I referenced from Forbes earlier. Check out some of these stats:

Countrywide Financial:
42% of its mortgage portfolio consists of pay-option adjustable-rate mortgages, in which borrowers decide each month how much to repay and can face negative amortization of the loan.

Washington Mutual:
33% of its loans through the third quarter of 2006 were pay-option or interest-only loans that tend to result in higher default and foreclosure rates.

Do either of those companies sound like they are focussed on helping people own homes? Maybe for the other 58-66% of the customers?

Frutmost, the best customer service ever

Upon reading this, I was reminded of the best customer service I ever received...

We had a wonderful experience with the owner of the company Frutmost. We had enjoyed their smoothies before from a Super Target, but one sunday when we bought one the thing had fermented, exploded over my wife in our car. We were so upset by the bad experience that my wife sent an email in to the company. Within a couple of hours, the owner of the company (on a Sunday, remember) had gotten the email on his blackberry, looked us up in the phone book, and called us to apologize and offer to send us free product, pay for dry cleaning, and pay for our car to be cleaned. Her clothes didn't need dry cleaned and the car was not so bad, but we took him up on the free product. On Tuesday we received, packed in dry ice, Multiple types of Frutmost and guacamole meals from the other food manufacturer he owned. It was the best customer service I had ever experienced or heard about.

Other issues with the lender laws changing..

Will any lender be able to give a 50 or 55 yr old anything but a 10-15 yr mortgage? Anything beyond that, they may sue and say it doesn't meet their retirement goals. So, I wonder if this will just give the lawyers more money and have all the lenders make you sign things that you understand what you are doing....or will the lenders reject certain people like the 50 to 55 yr old who wants to buy a new house. It sure will be interesting...

Raleigh, #1 city for jobs

Congratulations Raleigh...Forbes has released their annual best cities for jobs and Best first jobs for college grads They name Raleigh the #1 city for jobs and, my job, Software Engineer/Developer the #5 job. Awesome!

Monday, February 12, 2007

Lender (mortgage) laws reworked -- The mortgage nanny

Have I gone liberal? I read this article today and I am so glad that the Democrats are looking to rework the lending laws. This is great...but does it mean I have gone liberal?

Primarily, this bill will put responsibility on the lender to ensure the loan they are giving is suitable for the people. Normally I would disagree with a bill like this. Mainly, I would have, in the past, disagreed with this for two reasons:
1) I don't want the government interfering with private business with more laws.
2) This seems to open up for more potential lawsuits, which means we will all pay it in our mortgages.

Now, first let me say my mother was in the mortgage business for about 10 out of the last 11 years. So, nothing personal against the people...but the majority of mortgage brokers are all about one of two things:
1) Making as much money off people as possible.
2) Helping create an ownership society, where people can own a home instead of rent.

That may sound overly simplistic...but I honestly believe that is it. If a mortgage broker is in the latter category, they surprisingly align with many conservative values. Conservatives are about an ownership society...letting people have the money and developer wealth on an individual basis. If they are helping people, this won't be a burden to those people.

I believe that the majority of the mortgage brokers are in the first category...how can I make the most money off people. I have been appalled by stories from friends lately of what people are offered. Here are some examples:
- A friend was offered an 80/15 fixed/adjustable mortgage for 6/8% APR...when that fell through, the broker magically found a much better alternative... a 80/15 fixed/fixed for 6/7% APR. If you don't know what these mean, feel free to write me and I will clear it up.
- Another friend closed on a house a month later with a 75/20 fixed/adjustable for 6/9%. Why 75% and 20% instead of 80%/15%?? The only thing I can figure is the mortgage person found a way to make more money.
- Another friend thought they were getting their dream home....but after they closed on an interest only mortgage and can't afford to pay principal...they realized they all they can do is hope the house prices in the area go up.

I have noticed other tricks the more my friends by homes. One lender, Bank of America, is offering a 100% mortgage at 3/4 of a point over the going 30 yr rate...which means instead of paying PMI or a split mortgage until 20% is paid off...they will pay that 3/4 point for 30 yrs or until they refinance. How is that justice? Their monthly payment is lower...but the overall life of the mortgage is higher.

The bottom line is, as I see it as a late 20s guy whose friends come to him for financial advice from time to time...a lot of my friends have been or are potentially getting fleeced by the lending industry. This is not creating an ownership society.

So, back to my original question...am I becoming liberal? No, I don't believe I am. Like it or not, people are not well informed enough to know how the lending industry works and the lending industry does it on purpose. I support the current lawmakers making the government a bit bigger in this particular case because I believe that these laws may allow people to save and own more in the long run....and thats important to me so that when my generation is old, my daughter doesn't need to pay high taxes in order to support my generation which is blowing all of their money and won't have enough money or own enough later in life.