Showing posts with label Mortgages. Show all posts

Monday, January 12, 2009

Interest Rates

So, like many "homeowners" I have been watching the interest rates plummet and preparing to refinance. I finally began the process of refinancing on Tuesday when 15 year fixed rate mortgages hit between 4.25% and 4.5% locally. Heather and I are on an aggressive track to pay off our house and so we had to make sure our closing costs were as low as possible. I called many companies and here is my anecdotal occurrences with each of them:

  • One of my friends had luck with Citi using our employee referral program and I contacted them. I immediately had the phone answered and they took my name and number on Tuesday. On Thursday, after having not received a callback, I called again and got someone after less than one minute on hold. They quoted me nice rates, gave me their contact information, and told me they would be available Friday and Saturday morning. When i called Friday the lady's voicemail said she was on vacation.

  • Two companies never returned my calls - Wells Fargo and Chase.

  • The current company who holds my mortgage, HSBC, had rates 3/8 higher (4.875) than the next highest person I contacted (4.5%) and still wanted a full origination point.

  • My credit union, Coastal Federal, was the only one who came through. They had low closing costs, low rates, and gave me no hassle. You can check their rates here. They charges 1/2 pt origination, no discount points, no application fee, and I locked in a 4.5% 15 year mortgage which is a substantial savings from my current 5.875%. Overall closing costs were around $2100 which in NC seems to be a great deal.


Also on the interest rate front, the high interest online savings accounts are rapidly dropping their interest rates in the 2.5-3% range. My credit union has a pretty cool program called "Go Green Checking". The biggest issue I have is that who wants to put your real savings, like emergency savings and long term savings for cars, in a checking account with a card you use frequently. See, you have to use this card 12 times a month, which means you have 12 chances to get your numbers stolen. Sure, Visa says it will replace your money if stolen but reports say that this can take 2-4 weeks sometimes. This is my emergency savings, I don't know if thats secure enough for me. Thoughts?

Friday, August 08, 2008

The dream of a lake house


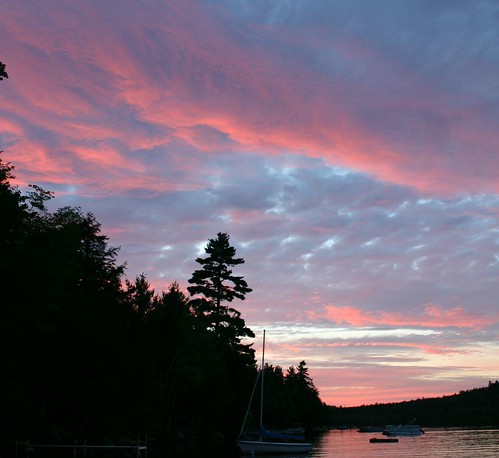
I was viewing a friend's pictures of their gorgeous lake lot and went down the rat-hole of looking into lakefront properties and the prices and viability of buying a lakefront home. I have been dreaming of owning a lake front property for years. It probably all started when going to my sister's in-law's house in Maine. (The picture above is from that lake house when Heather and I visited there in 2004). Heather and I also enjoyed multiple relaxing weekends in Virginia at her uncle's river house. These non-beach but very nice vacation homes have given us something to dream about for our future...

The problem is, as you know if you have been following my blog, I don't want any debt...let alone on a house we don't use frequently. Our ability to save up the money to buy a house will be near impossible in the next 10 years while meeting our other financial objectives relative to our primary residence, retirement savings, college savings, and schooling for our children.

I have to admit, the thought of waiting for 15-20 yrs to have my dream vacation home kind of stinks. Anyone else have a similar dream they are holding off on?

Wednesday, August 06, 2008

Good article on the new tax provisions in the housing bill


I finally found a good article about the new tax provisions in the big housing bill that was signed last week. Although each of the provisions targets a very select audience, I thought I would try to summarize:

1) If you are a first time home buyer (did not own a primary residence for 3 years prior to this purchase) between April 9, 2008 and July 1, 2009, you can get an interest free loan of 10% on the house up to $7,500. It comes in your next years taxes as a tax credit and must be repaid starting in the second year for 15 years. You can't make more than $95,000 for singles and $170,000 for couples and the credit is reduced for those above $75,000 and $150,000.

2) If you own a home but don't itemize your deductions and therefore take the standard deduction, you can property taxes on your home above the itemized deduction of up to $1000 for couples and $500 for individuals.

Those are the "helping" provisions. To pay for this, there is a third provision which is a tax hike. Here is a quote from the article describing that tax hike:


To pay for the new breaks, Congress adopted some revenue raisers, otherwise known as tax hikes, including one that affects homeowners. At present, taxpayers who own a vacation or rental property can begin using it as their principal residence and then sell it after two years, taking advantage of the break that excludes from income capital gains from the sale of a principal residence. The excluded amount is up to $500,000 for a couple or $250,000 for a single.

But thanks to the new law, after January 1, any time a house isn't used as a principal residence it reduces the gains eligible for exclusion on a pro rata basis. So, if a couple uses a house as a vacation or rental home for five years and then as a principal residence for five years, only half their gain will qualify for the exclusion.

If the couple has a $100,000 gain, they can only exclude $50,000 of that gain from their income. But if the same couple owns a mansion and sells at a $1 million gain, they can still claim the maximum $500,000 exclusion, because it's just half of their gain.

An odd result from a law that was supposed to help struggling, ordinary homeowners.


Well, it looks like that hurts people also that maybe haven't been able to sell their home because of the bad market. For example, if they moved from a house they lived in for 4 years and established another primary residence, and didn't sell their home for 1 year after that, they would only be able to exclude 80% of their gains regardless of the fact the last year of house taxes have been dismal. That's how I read it, but I am no tax professional. I think this is going to hurt a lot of people who already were hurt by the housing market.

Tuesday, June 24, 2008

Paying down house vs Saving for retirement

I thought this was an interesting video from Fox Business debating whether to pay off your house or saving for retirement. The argument for saving for retirement was:
1) Lots of expenses when you are retired.
2) Housing is one of the few fixed expenses
3) You can make more after tax on your house.

The argument for paying down your house:
1) Emotional security of having the house paid off.
2) Expenses are down significantly with the mortgage paid off.

The guy arguing for paying down the house, Craig Carnick, did a poor job. His whole argument was emotional security. Ignoring that a bad couple of years in market like we might be seeing now could kill you in retirement if you are planning on that money to pay your mortgage. Not to mention the fact that when you are in retirement, you reduce he risk of some of your portfolio which makes beating the after tax mortgage payment with your after tax investments more difficult. Plus, a person making this decision probably has gotten their mortgage to the point they are paying a lot more principal rather than interest, meaning that "free" money from interest is probably not that much.

Ohh well, I do agree with Craig Carnick in that the paying off your mortgage reduces your expenses and allows you to have much more flexibility to maneuver around and meet your needs in retirement.

Thursday, June 19, 2008

How much of a house can you afford?

Many experts say that your mortgage payment (principal+interest+tax+insurance) should not be more than 25% of your gross income. If you listen to the likes of Dave Ramsey, that mortgage should be no more than a 15 year fixed rate. But, I was looking at what different salaries could afford (maximum) as a 30 year fixed rate under this plan:

$40,000 salary - $122,000 mortgage ($833/mo)
$60,000 salary - $183,000 mortgage ($1250/mo)
$80,000 salary - $244,000 mortgage ($1667/mo)
$100,000 salary -$305,000 mortgage ($2083/mo)

If you change it to a 15 year fixed as Dave Ramsey suggests:
$40,000 salary - $90,000 mortgage
$60,000 salary - $135,000 mortgage
$80,000 salary - $180,000 mortgage
$100,000 salary - $225,000 mortgage

The assumptions I made were that the interest rate was 6%, taxes at 1%, and I used this calculator which adds in insurance. This assumes also a 20% down mortgage with no PMI. That mortgage calculator incidentally doesn't allow you to go over 28% of your gross, which isn't that much more than the 25% rule. It also allows you to indicate other debts.

Tuesday, May 20, 2008

The advice is general, not specific

I Googled recently for Dave Ramsey's credit card study information and found lots of blogs spreading anti-Dave Ramseyisms and I realized that people just don't get it. Dave Ramsey provides general advice which can be applied to everyone. That doesn't mean every piece of advice is the best for everyone, but its good for everyone. For example, someone called in to his show a couple month's ago and asked about 529s. He admitted on the show that not all 529s are bad, but some of them are so its easy to just say avoid them all. Looking into it, I found that some states limit investment choices and charge high fees for their 529s. If you are in a state where you can invest in a mutual fund with a long track record (10-15 years) that has low fees and get a tax deduction for doing so, I believe he would say that is a good choice. But, since not all states and 529 plans are like that, its easier to suggest other investment methods when they exist and also are tax advantaged.

Other areas where I think he gives general advice are the amount to save on retirement and never to use credit cards. The amount to save for retirement he suggests is 15% (once consumer debt is paid off) of your gross income. Advice can't possibly be global like that and perfect for everyone no matter their age, salary, and family situation. So, he gives the best rule of thumb, 15%. You can calculate how much you will need for your particular lifestyle, salary, and age and probably come up with a better figure for yourself. But, if you can't figure it out, 15% of gross will probably work.

Another example is credit cards. Dave says the following:

You’re also paying more. A study by Dunn and Bradstreet showed that the credit card user spends 12 to 18% more when using credit instead of cash. After McDonald’s began taking credit cards, they found that people spent $5 to $7 more per sale.

If someone was disciplined and got a credit card purely for gas purchases making 5% cash back (instead of rewards they will never use)...I doubt they would buy 12-18% more gas just because they are using the credit card or they will buy gas from places with 12-18% higher prices than they would have with using cash or a debit card. The fact is most Americans are not this disciplined. So, a better general rule is to avoid the credit card altogether.

Would Dave agree with that? Not sure, but I believe it :-)

Monday, April 28, 2008

Investment or Mortgage

I had a conversation with a friend this morning about how poorly our 401ks have faired this year. Although they are almost breaking even for the year, the market volatility had me thinking...

One of the popular questions people ask is whether it is better to push money into investments or on to your mortgage. Some financial advisers will tell you to put it into investments which will get you 8-10% while you only pay 6% on your mortgage. Others will point out the tax advantages of the interest on your mortgage, while ignoring the tax implications on your investments. Either way, working out the numbers you can make more if you assume an 8-10% return than you spend would on a 6% mortgage.

Other financial advisers, like popular anti-debt talk show host Dave Ramsey, will tell you to fully fund your 401k and Roth IRAs before paying off your mortgage. Fully funding, according to Dave Ramsey, means 15% of your gross income towards Roth IRAs and your pre-tax retirement accounts like IRAs and 401ks. At that point, he would tell you to put it towards your house debt because you wouldn't take equity out of your home to put it in the stock market, would you? The answer is, you especially wouldn't do so now.

The key is that the 8-10% return on investment is projected and you will not find guaranteed interest higher than your mortgage. The market has proven its volatility this year and you would have struggled to get over 5% back on stocks, mutual funds, through money market/savings accounts, or through CDs/bonds this year so far. Yet, most of us with mortgages have primary mortgages somewhere between 5-7% with some secondary mortgages from 7-10%. So far this year, paying off your mortgage would have been the better financial decision. In the end, paying down your house also brings more financial stability to your family and more freedom overall.

An executive who I reported to around 2004-2005 when hearing I was purchasing a house made the comment that he hopes it was a big mortgage, cause "thats how we lock in our employees." Was he joking? He said it jokingly, but there was some truth behind that joke. Many people rely on their salaries to pay their mortgages and couldn't take a pay cut. If you had your house paid off, you might be able to support your family while working a lower paying job. That helps financial stability. Also, you might be able to choose to do something you love rather than what you put up with. :-)

Finally, imagine what you can do with an extra mortgage payment in your pocket every month. Let's say you have a low mortgage payment of $1000 per month. If you could invest that over the next 10 years instead of use it to pay off your mortgage, in 10 years at 10% annual return your would have over $205,000. Try it with your mortgage numbers using this Investment Calculator.

As my friend concluded our conversation today, "That guaranteed 8% by paying down my [second] mortgage is sounding pretty good about now."

Saturday, April 26, 2008

Legislating against predatory lending

I have said in the past that I was all for legislating against predatory lending practices. However, this Forbes commentary makes a good point about the current legislation, which is not very specific, may hurt more than it will help. If you need some background on predatory lending, this this Forbes article provides a lot of background like this statement:

Three market conditions are associated with predatory lending, Musto and his colleagues found: There is little competition among lenders, property owners are sitting on lots of equity and borrowers are poorly informed about risks. In casual conversation, predatory lending usually means a loan that is bad for the borrower. "But this begs the question: How do such loans arise in the first place, when borrowing is voluntary?" Musto and his colleagues write.

To many people, loans with extraordinarily high interest rates constitute predatory lending. Critics often cite payday loans, which charge the annual equivalent of more than 100% for loans in advance of a worker's next paycheck. Loans putting borrowers at high risk of default also are often called predatory. This would include "negative amortization" mortgages that allow borrowers to make very low monthly payments, causing the outstanding balance to grow over time rather than get smaller.


The first article makes the claim that the free market has corrected itself:
When bad loans are made, both borrowers and lenders are punished--and must correct course. Observe that Wall Street financial firms and direct lenders who engaged in lax lending are suffering huge losses (such as Merrill Lynch's (nyse: MER - news - people ) $8 billion loss) and internal upheaval--and have changed their practices accordingly. The number of subprime, adjustable-rate mortgages has declined by 50% this year. As for the middlemen who tried to make (and often succeeded in doing so) a quick buck on dubious loans, their reputations are sullied and their business has dried up.


While I believe that it is the case that the market has corrected itself for now, what is to prevent it from getting back this way. These practices have cost everyone in the US money as taxpayers are bailing out the mess that the commercial lenders created. How can we ensure that we do not again get in a situation that our taxes will be used to bail out predatory lenders? The only way I can figure to do that is through legislation. Maybe this legislation isn't the right legislation, I must confess to not having read through it, but I don't again want to pay for these bank's mistakes.

Friday, March 28, 2008

Maxed Out - American Economy's Credit Woes


I wanted to see the documentary Maxed Out on the American Economy's Credit problems, too expensive houses, cars, way of living, and the effects it has on people. It was eye opening and worth watching. The good news is, you can apparently see it for free on Google Video here. I recommend checking it out.


Maxed Out as a documentary was very well done although I am not sure I agree 100% with the direction they took on it. They did not blame consumers or lifestyle creep as much as I think needs to be blamed. Instead, they seemed more prone to blame cost of living, the banks for offering credit and loans, and the government for not stopping the banks. For example, they point out that people have less money today than they did in the 1970s if you cost-adjust things for inflation. While that might be true, people are tending to live more lavishly than they should be as well.

As my friend Aaron said, "The system is set up for people to fail, but still, if [those people] could do basic math they should know that."

Speaking of lifestyle creep, its interesting that many of my friends tend to live in or purchase houses that are larger than those they grew up in. Are we more successful than our parents or more in debt? I think its a little bit of everything, interest rates back in the 1980s and 1990s were less, some of our parents maybe weren't as successful, now many more people do 100% financing and are more in debt, and finally I think that the new houses these days are built larger for less money but done so also with less quality.

All that said they do point out that the government debt is astonishing and needs to be taken care of, a point that a fiscal conservative such as myself wholeheartedly agrees about.

Amortization schedules show the real problem

Financial Advisors love to flaunt the power of compound interest, that is the amount of interest money can earn over time when you earn interest on the principal and interest that exists. If you look at an amortization schedule, you will see the opposite, almost a negative compound interest thing happening.

First, an example. Using an Amortization calculator and Freddie Mac's current weekly average mortgage rate of 5.85% on a 30 yr loan starting in April of let's say $150k, you will find I would pay off the first half of principal in February of 2029 making the minimum monthly payment. Thats almost 21 years to pay off $75,000 at almost $900 per month! By the end of 30 years, the total interest paid is over $168k!

While changing the principal doesn't change when you pay off half, your interest rate does. If you have a higher mortgage rate, lets say 7%...you pay off half in December of 2029. So, when you pay off your first half of your mortgage varies from about 20-22 years based on the current interest rates.

Now, in the past people have paid little to no attention to these schedules. Its because paying off principal wasn't an issue when houses were growing at 4% compounded annually. But, with the recent housing market growth slowdown, I hope that more people pay attention to it. If someone gets a 100% financed $150k house now and prices only go up 1% per year for the next 3 years and then they try to sell it, they will have paid off roughly $6.5k in principal and gained about $4.5k in value on their home. So, if they sell it at that $154,500 with a standard Realtor fee of 6%, they will pay $9,270 in Realtor fees. This will leave them with a whopping $1,730 check for paying $32,400 in mortgage payments not including PMI, homeowners, and taxes. Sure, they will also have got a small tax deduction during that time...but I think they might have been able to rent and save more money.

Just as a matter of opinion, look at your amortization schedule and consider dropping some more money into your mortgage monthly. Maybe you can pay off the first half a bit quicker than in 20 years then :-)

Wednesday, January 23, 2008

Refinancing

Heather and I have been considering refinancing our house but found that the fees of our current lender, HSBC were higher than we had though they would be ($2200). The first thing I did to see if refinancing made sense was to try the Bankrate.com refinancing calculator. Well, this calculator bases whether it makes sense on how much you would save on your monthly payment...not how much you pay monthly or when you will pay off you house and how much you will actually save. I thought this calculator was useful for someone planning to go to full term on their loan, but not someone that is looking to pay off the loan early. So, I had to go to Excel and adjust my amortization to change the rates, payment levels, and either have the new rate or the current rate plus $2200 paid immediately..plus calculate tax advantages of the different rates. What a pain, I may just have to write a web application to do this for people. In the end, $2200 paid immediately for us was a better fit rather than refinancing.

Thursday, January 17, 2008

Time to refinance?


What should be good news to the ailing mortgage industry is that the talk of the office today was whether or not to refinance their homes for those that bought houses in the past 2.5 yrs. Bankrate.com has the going rate at 5.42% and our current lender and bank, HSBC, had a rate posted of 5.50% earlier this year. For those that would be waiting for lower rates like me, I suggest you try the bankrate alerts where you can specify the rate you want alerted at.