Anna likes to attack us when we take pictures of her, so when getting a picture of her dressed nicely for a dinner party last night in her new shoes and a dress daddy picked out, she got real close and you can see her green eyes. Here is our green eyed beautiful girl:
And here she is in her dinner party dress:
Sunday, April 20, 2008
Green Eyes Redux


Friday, April 18, 2008
Personal Responsibility in Finances
Listening to Dave Ramsey and watching Maxed Out have reiterated in my mind the need for personal responsibility in finances. When I was at the highest point of debt I had, it was due to my own miscalculations, stupid decisions, and lifestyle. I didn't blame the credit card companies, the car dealerships, the price of higher education in this country, or the housing market for the debt I had, but rather I accepted that it was my personal decisions that led to credit card debt, car loans, student loans, and a mortgage at an age that was entirely too young, 22 years old. I liked high tech toys and spent too much on them. I liked cars, and had two of them. I spent my earnings while in college on eating out and having fun rather than on the necessities that my student loans paid for. All of these were dumb decisions.
What's amazing is the numbers of people who do blame these other factors and are not willing to own up to their decisions. Even Maxed Out, which was an eye opening movie talking about the state of debt in the country, puts the blame squarely on the shoulders of the credit card companies for offering too much credit or to people who are too young, for credit collectors for harassing people, and to the federal government for not regulating the big businesses offering loans and credit to the people. Granted, many collectors may be the scum of the earth and I think Maxed Out proved that nicely, but if a person were not in debt in the first place, they wouldn't be coming after them.
I realize that others get in debt out of necessity. They may have lost their job or got very sick. But again, the debt wasn't the fault of the credit card companies. It probably wasn't the fault of the federal government, although I am sure there were cases where it was, but the government regulating banks lending closer would not have helped those situations often.
I think in the end a lot of consumer debt is because people are living a lifestyle they can't afford. Not all, but a lot. I just wished people took more personal responsibility in those cases.
Wednesday, April 16, 2008
Green Eyed Monster
Last Friday, Anna has her 18 month check up as reported by my wife. The doctor declared Anna's ever changing eyes "green" and it looks like they will stay that way. Green I think means they can look brown, can look blue...or can look green. Here are a cute couple pictures of our sweet girl...the first looking shy and not like a monster...
Or is she a monster that wants to eat you? (This is Heather's favorite)
According to Wikipedia, the internet source of knowledge:


Green eyes are the product of moderate amounts of melanin. Only 1-2% of the world's population has green eyes and is the least common eye color. Green eyes are most often found among people of Northern and Southern European origin, and to a lesser extent, in the Middle East, Afghanistan, India and other countries with a predominant Caucasian population. Many Irish people are found to have green eyes. Other countries like Iceland, Sweden, Denmark, Finland, Norway, Germany, and the Netherlands have a high percentage of green eyes.
At least she will be fairly unique in her eyes...
Tuesday, April 15, 2008
Babpah Babpah -- Anna's talking skills
Anna's been working hard on her listening skills and tonight during our date night, I heard her working on her talking skills for the first time. For over the past month, Anna has been listening and responding to many questions and statements. Every day she seems to pick up something new. Tonight after her bath while Mommy was at water aerobics (Yes, less than two weeks before she is due Mommy is still doing water aerobics!) Anna and I were watching Dora the Explorer.
During Dora, when she needs something (like a towel tonight) they sing a song that goes "Backpack, Backpack." Knowing this from when my niece was younger, I started singing along which thrilled Anna. A couple of minutes later she looked at me and said, "Babaa." At first, I thought this was the "Buh-Bah" she has been calling Mommy instead of "Momma." So, I asked her, "Momma?" She said no and said, "Babpah." I thought for another second and said, "Backpack?" She said, "Yea, Babpah Babpah!" She was so excited and kept saying it. So I went and got her backpack and said, "backpack." She then wanted to wear it which i let her and she walked around saying "Babpah."
Here is a month old picture of Anna wearing her "Babpah"...

Monday, April 14, 2008
Good news on the baby front..
As you can read in Heather's blog, all is well on the baby front. She is progressing further (2-3 cm dilated), gained a pound, and the measurements that caused us concern last week don't concern the doctor. It would have been nice if they told us that last week! We expect our new little girl soon!
The doctor said since Anna came out so easy, we better get to the hospital quick since this baby is smaller and Anna was just 18 months ago. Great...another stress point... :-) I'd rather worry about getting to the hospital though than the health of our baby.
Obama calls those in depressed region of the country gun bearing hate mongers
After reading this NY Times article and seeing these quotes from presidential candidate Barack Obama, he went from someone interesting on my list to someone I would absolutely never even consider voting for. Specifically, it was this statement:
“You go into these small towns in Pennsylvania and, like a lot of small towns in the Midwest, the jobs have been gone now for 25 years and nothing’s replaced them,” Mr. Obama responded, according to a transcript of the fund-raiser published on Friday on The Huffington Post Web site.
“And they fell through the Clinton administration, and the Bush administration, and each successive administration has said that somehow these communities are gonna regenerate and they have not,” Mr. Obama went on. “And it’s not surprising then they get bitter, they cling to guns or religion or antipathy to people who aren’t like them or anti-immigrant sentiment or antitrade sentiment as a way to explain their frustrations.”
As my friend John summarized this comment, "So they are gun bearing hate mongers because the area has no jobs."
I am not going to say anymore but maybe we are seeing who Barack Obama really is now with these sort of comments...
Thanks to Rhys for alerting me to this.
Also, check out this Pittsburgh blog response
Sunday, April 13, 2008
Growing up..
Anna is growing up too fast...she understands all sort of questions, answers yes and no questions, and picks up on lots of little words you say. Today, i said look at that bird and she looks up in the air. I said ball and she didn't move, then I said balloon and she immediately pointed at it. She likes to wear bows in her hair, sunglasses, and other such older kids things. These pictures remind me of how much she has grown up...here is one of her from today and one from a year ago...


Friday, April 11, 2008
Anna's playpace redux
I know I said I was done with the Anna's playplace blogs, but I have spent more time and wanted to share the things I learned.
1) 2-3" of mulch gets moved really easy by sliding toddlers, running dogs, and any combination of the two running or jumping. We bought another cubic yard of playground mulch to spread on top.
2) I measured the perfect amount of sod, but the beautiful sod made the close by not so good looking grass look bad. So, plan to replace the not so good looking grass as well next time. I had to get 5 more rolls of sod.
3) If your child loves playing outside like ours, you will spend a lot of time out there. Plan to buy a bench. We had planned to buy one, but we did it a lot sooner. Good thing too, because Anna and my poor pregnant wife averaged probably four hours per day outside this past week.
Here is an updated picture...

Tuesday, April 08, 2008
Creamy Cheese Lasagna
So, I am in the recipe posting mood. Here is a favorite...Last year I set out to make a creamy cheese lasagna like my good friend's mom used to make. I read about 80 recipes and came up with my own. My friend, John, told me it was the second best he ever had behind his mom's. So, I thought I would share the recipe.
The one trick I did learn was to cook it, let it sit to congeal, then heat it again. This is how it stays together when you cut it. This works nicely also if you are bringing it to a friend as you can do the last heating at their house hours later.

1 box of lasagna noodles (16 oz)
1.5 c mozzarella
1.5 jar of sauce
------------------------------
------
Cheese Mixture
1 c parmasean finely grated
1 lb ricotta
1 c romano finely grated
3 eggs
1 clove garlic minces
basil (more basil than parsley or oregano, fresh if possible)
parsley
oregano
--------------------------------
Spray 8x12 - 9x13 pan with cooking spray. Cover the bottom of the pan with sauce light layer of sauce
Start with a layer of noodles (4-5). First and last layers should have the most noodles.
Put 1/3 cheese mixture on the noodles. (Lowest layer should have least cheese)
Approx 3/4 c of sauce on that. Place 4-5 noodles on that.
Another 1/3 cheese and 3/4c sauce.
On last layer, put 1/2c mozzarella on top of sauce. Put final layer of noodles.
Then put remaining mozzarella and then sauce on that. Should be covered in sauce on top.
Bake at 375 for 35 mins covered, 10 mins uncovered. Let sit on counter for 4 hrs uncovered to let it congeal.
Bake again at 350 for 20 mins.
Anna is a slider
We learned probably 5-6 months ago that Anna is a slider. What I mean is that every kid has some sort of specific entertainment that they are drawn to. Some kids love jumping, swinging, running, climbing, building, etc. Anna is a slider. She loves sliding. She will always slide. When she is upset, we say, "Can you go and slide?" She will hobble over, sometimes still crying, and by the time she is at the bottom of the slide...she has a smile. We have an indoor slide that Heather has blogged about. We also have an outdoor slide in her new play place. Here is an action shot of her sliding on it from just before lunch this morning.
Why kids choose these things, I doubt we will never know. But we know that for now, Anna has chosen her slide as the activity of choice. Here are some more of Anna sliding in the past 5 months...


Hot Fudge Sundae Cake
After adding the Dump Cake recipe, I decided to post another dessert for those chocoholics. Another Burckart family favorite is our hot fudge sundae cake. Years and years ago, my mom got this recipe off a Hershey's container and its survived in our family ever since. Hershey's calls it something different now, Hot Fudge Pudding Cake, and uses butter instead of Crisco, but its still excellent.
Not only is this a great treat, but its fun to watch it be made also. You make the cake, then dump sugar and cocoa on top of the cake and pour hot water all over it. So, what goes in the over is a cake with a pool of water over the top. But when it comes out, the water has crept through to the bottom making a layer of rich fudge underneath the cake. Yummy!

Hot Fudge Pudding Cake
Ingredients:
* 1-1/4 cups granulated sugar, divided
* 1 cup all-purpose flour
* 1/2 cup HERSHEY'S Cocoa, divided
* 2 teaspoons baking powder
* 1/4 teaspoon salt
* 1/2 cup milk
* 1/3 cup butter or margarine, melted
* 1-1/2 teaspoons vanilla extract
* 1/2 cup packed light brown sugar
* 1-1/4 cups hot water
* Whipped topping
Directions:
1. Heat oven to 350°F. Combine 3/4 cup granulated sugar, flour, 1/4 cup cocoa, baking powder and salt. Stir in milk, butter and vanilla; beat until smooth.
2. Pour batter into ungreased 9-inch square baking pan. Stir together remaining 1/2 cup granulated sugar, brown sugar and remaining 1/4 cup cocoa; sprinkle mixture evenly over batter. Pour hot water over top; do not stir.
3. Bake 35 to 40 minutes or until center is almost set. Remove from oven; let stand 15 minutes. Serve in dessert dishes, spooning sauce from bottom of pan over top. Garnish with whipped topping. About 8 servings.
The changes we make to it is that it serves like 6 and to use ice cream, spooning the hot fudge on top of the ice cream.
News on the baby front
Our next baby girl is healthy albeit very small according to the ultrasound this morning. She was 5 lbs 13 oz and in the 18th percentile with less than 3 weeks to go. I take this as good news that she is healthy. She is very tight in there and head down. The doctors said typically they like to see half a pound a week, which would put her right around 7 lbs when she is full term.
Heather and I are no longer wishing that she comes early since she is so small. We'd like her to stay in there a while longer to allow her the maximum time to grow. Although its tough since she is so tight in there and causes Heather a lot of pain when she moves.
Monday, April 07, 2008
North Carolina Dump Cake
Tonight, Heather had a craving for dump cake. The first and only time we made this was on Groundhog's day this past February, which happens to also be my good friend Derick's birthday. He just so happened to stop by with his mom and dad, and we all had dump cake for his birthday. Then, we had it the next night for the Super Bowl. Well, we are making the same recipe again and I thought I would share it for all of you who have never heard of such a thing.
Spray a 9x13 or 8x13 pan. Dump (Put) each of the following on as layers in order:
20 oz can of crushed pineapple including juice
2 cans of cherry pie filling
1 box of yellow cake mix
(optional) sprinkle coconut on the top
1 stick of butter melted and drizzled evenly over the top.
Bake at 350 degrees for 48 minutes.
Serve warm will vanilla ice cream.
You can substitute the cherry pie filling for other types of pie filling.

3 weeks to go...
Heather is 37 weeks pregnant today with three weeks to go. Unfortunately, she is not growing as well externally as the doctor would like (has still gained < 15 lbs) and so they ordered an ultrasound for tomorrow. Last time we had an ultrasound for the same reason, they found the little girl was growing regular and in the 51% for body. We are praying that they will find the same thing tomorrow. More news on this tomorrow...
We have just about everything ready for our new little girl to come home to. Heather has washed the clothes and the room is clean and ready. Heather has a bag to pack and we have a variety of people prepared to watch Anna while we run to the hospital. The car seat base is back in the Pilot. All we have left is to set up the bassinet and raise the crib...but since I will be home with Anna after the baby is born, I can set it up then.
Heather and I have been continually been making commitments with clauses such as "so long as the baby does not come." I even have been doing this a lot at work. At work, I try to finish all of my longer term deliverables immediately so that I don't have anything outstanding should the baby come.
Its really a new mode of thinking throughout, an anticipation in all of our lives. When will she come? Only God knows. But, those of us down here cannot wait!
Friday, April 04, 2008
Anna's completed playplace (in pictures)
Anna saw it immediately and was excited after her nap. Here she is climbing on it the first time
And looking through the side
First zoomed out view from the back porch
Second zoomed out view from the back porch
Cassie wants to get on it as well!


Part 5 of Anna's playplace - Complete
We are done!!!
1.5 cubic yards was the perfect amount of playground mulch. It took a about 30 minutes to move and spread with Heathers help (don't worry, she just pushed the mulch around after I dumped it!)...
Then, we assembled the Step 2 playset. Wow was that easy! Snap together and 4 screws completes the task.
We are eager for Anna to wake up from her nap so that she can try it out!
Running total including tax:
Dirt: $135
Seed, weed barrier, and tools: $55
Sod: $125
Playground mulch: $50
Playset: $290
--------------------
Total: $655


Part 4 of Anna's playplace
Our lawn person happened to come Thursday and mentioned that we would be dealing with a lot of mud based on the shade in that area and suggested we just sod it. She mentioned getting good sod at Super Sod which is just down at the farmer's market and sells sod in smaller amounts than by the pallet. John helped with his pickup and we got 25 rolls of sod, each of which covers 9 sq ft. We laid it out and now we have sod around the playplace:
We also picked up 1.5 cu yds of mulch, all his Honda Ridgeline would hold. I should have it all done by this weekend!

Thursday, April 03, 2008
I don't drink coffee

At work, we have several places to get coffee without leaving the building depending on how much of a connoisseur you are. There is the lowest level, the free stuff available in every break room on every floor. The middle level is available only in the mornings in the cafeteria. And the highest level is available in the convenience store is Starbucks. All that said, I often hear "Let's get coffee" when someone wants to talk in the morning. Furthermore, its the same people offering to get coffee with me again and again. It also nearly never fails that they ask, "Aren't you getting coffee?" when I do not myself pick up a cup wherever we end up. I've decided I need a t-shirt or sign in my cube that points out that I don't drink coffee as a reminder to these people. :-)
Floored this morning..
This morning I was reading our friend Julie's latest blog posting and was absolutely floored. I think two things really hit me this morning:
1) How wonderful and selfless Julie is, to show so much concern for others in the midst of such tough times they themselves have gone through in the last year. Julie's son Ethan was born with HLHS, Hypoplastic Left Heart Syndrome, meaning he essentially is missing half of his heart. He is doing great, but the family has been through a lot including two surgeries for Ethan in less than 9 months and staying at the Ronald McDonald house in Chapel Hill to be near their son. This isn't the first time that Julie has asked for prayers and focus on other families through her blog...and I think that shows an amazing attitude. Many people when faced with a tough situation tend to focus on themselves, but not Julie...
2) I read through the blog she referenced yesterday, Confessions of a CF (Cystic Fibrosis) Husband and again was hit as to how blessed Heather and I have been with good health. The strength of this 27 year old man I do not know who has a two (almost three) month old premature child and a wife battling to live is amazing in this blog. Its like a book I can't put down. I can't imagine going through what he is going through with such dignity and hope, but I pray that if I ever find myself in such a situation that God will give me the strength to do so.
For now, I just ask for you to pray for Julie and her husband Dan and their son Ethan as well as Nate, Tricia, and their little daughter Gwyneth.

Wednesday, April 02, 2008
Part 3 os Anna's playplace
Anna's playplace is almost complete. Today I installed the weed barrier as discussed in my last post. We also purchased the Step2 Naturally Playful Woodland Climber at Woodplay of the Carolinas today. Amazingly enough, the box fit into my Toyota Matrix with the back seats down.
Unfortunately, The Mulch Masters where I planned to buy the playground mulch from won't deliver less than a 5 cubic yard group of mulch and I don't have a pickup truck. The first time I could borrow a friend's pickup between the hours of 7 AM and 5 PM when they are open was on Friday...so no mulch yet means Anna can only play on the weed barrier...hence the pictures above :-)


There should be a rule...
That the first 10 Sunny Days of the year where the weather is between 65-80, you get the day off. Working is difficult on a day like today.
And while I am at it, I want a rule that says all coworkers should have access to natural sunlight in their primary work environment...
Monday, March 31, 2008
Part 2 of Anna's playplace
I continued the work on moving topsoil during the rain Sunday afternoon. All of the topsoil is now moved and the rains continued and got harder. The rain is supposed to continue all week, so I am praying that all my topsoil doesn't get washed away. The good news is that the area doesn't get hit hard by rains due to the tree cover. Here is a picture of the area with all the topsoil moved now:
The next phase of Anna's playplace is to put down a weed barrier. 
If this week lightens up on rain, I will be ordering 2 cu yds of playground mulch and getting the project finished. Meanwhile, in the areas around the play place I am fertilizing and planting grass. Since we are in a drought, the rain will provide the opportune moisture to get my grass started growing. Hopefully the area will be completed by this weekend.

Sunday, March 30, 2008
Back-breaking project -- Anna's play place
I have a cool project I am in the midst of at our house, too bad I woke up this morning with a sore back from it. In our backyard as you come off the deck, we used to have a brush pile and a bunch of trees. We had to get rid of the largest pine and while they were at it, the tree company offered to take away our brush pile. We gladly let them take this away and instead of piling more debris there, we decided the area made for a perfect play place for Anna as its shaded and close to the deck. At the same time, we decided we would reclaim some of the existing "garden" and make it into more grass in the back yard.
The problem is that the area is still covered with a layer of leafy mulch, no thicker than three inches. The area was also not as level as we like. Further, we couldn't see the area because of some overgrown bushes. Yesterday, I started to tackle all of these issues.
First thing yesterday morning, I moved the bricks delineating our garden and exposed more of what was declared garden to the "grass" side. I then spread out the leafy mulch, more evening the land. The land with leafy mulch on it was too soft in general and it would need covered in dirt to solidify the ground while the leafy mulch decomposes, much like how a landfill works but with less dirt. Then I hacked back the bushes at the end of the deck, too much from Heather's viewpoint, but in a way that hopefully should allow them to grow back and us to have a better view of Anna's new play place. This generated so much debris that I had to call John over to bring his truck and help me take it to the landfill.
By the time I got back, I had to take a break because it was raining and there was about to be a baby shower at our house, meaning I needed to clean up and be ready to take care of Anna. While the ladies were downstairs at the baby shower and Anna was asleep, I called and ordered 3 cubic yards of topsoil from Mulch Masters to put over this area. Around three hours later, the topsoil shows and I had my large pile of topsoil. Our guests left around 5 PM and I took advantage of the remaining daylight and lack of rain to start moving topsoil. I got about one and a half hours of moving topsoil in before the rain started again, but I feel good about the progress that was made. I took this picture this morning:
On the right you can see the light grey bricks with the new delineation of the garden. Everything between those 4 trees, about 12.5' X 13.5' will become Anna's playplace. The remaining area thats not grass will be covered in topsoil and have grass planted on it.
Once I finish moving the topsoil, I plan to cover Anna's area with a weed barrier and then playground mulch. We then hope to get some of the plastic play structures like this to put in there:
We still have a lot of work to do, but I plan to track some progress here :-)

Friday, March 28, 2008
Maxed Out - American Economy's Credit Woes
I wanted to see the documentary Maxed Out on the American Economy's Credit problems, too expensive houses, cars, way of living, and the effects it has on people. It was eye opening and worth watching. The good news is, you can apparently see it for free on Google Video here. I recommend checking it out.
Maxed Out as a documentary was very well done although I am not sure I agree 100% with the direction they took on it. They did not blame consumers or lifestyle creep as much as I think needs to be blamed. Instead, they seemed more prone to blame cost of living, the banks for offering credit and loans, and the government for not stopping the banks. For example, they point out that people have less money today than they did in the 1970s if you cost-adjust things for inflation. While that might be true, people are tending to live more lavishly than they should be as well.
As my friend Aaron said, "The system is set up for people to fail, but still, if [those people] could do basic math they should know that."
Speaking of lifestyle creep, its interesting that many of my friends tend to live in or purchase houses that are larger than those they grew up in. Are we more successful than our parents or more in debt? I think its a little bit of everything, interest rates back in the 1980s and 1990s were less, some of our parents maybe weren't as successful, now many more people do 100% financing and are more in debt, and finally I think that the new houses these days are built larger for less money but done so also with less quality.
All that said they do point out that the government debt is astonishing and needs to be taken care of, a point that a fiscal conservative such as myself wholeheartedly agrees about.

Amortization schedules show the real problem
Financial Advisors love to flaunt the power of compound interest, that is the amount of interest money can earn over time when you earn interest on the principal and interest that exists. If you look at an amortization schedule, you will see the opposite, almost a negative compound interest thing happening.
First, an example. Using an Amortization calculator and Freddie Mac's current weekly average mortgage rate of 5.85% on a 30 yr loan starting in April of let's say $150k, you will find I would pay off the first half of principal in February of 2029 making the minimum monthly payment. Thats almost 21 years to pay off $75,000 at almost $900 per month! By the end of 30 years, the total interest paid is over $168k!
While changing the principal doesn't change when you pay off half, your interest rate does. If you have a higher mortgage rate, lets say 7%...you pay off half in December of 2029. So, when you pay off your first half of your mortgage varies from about 20-22 years based on the current interest rates.
Now, in the past people have paid little to no attention to these schedules. Its because paying off principal wasn't an issue when houses were growing at 4% compounded annually. But, with the recent housing market growth slowdown, I hope that more people pay attention to it. If someone gets a 100% financed $150k house now and prices only go up 1% per year for the next 3 years and then they try to sell it, they will have paid off roughly $6.5k in principal and gained about $4.5k in value on their home. So, if they sell it at that $154,500 with a standard Realtor fee of 6%, they will pay $9,270 in Realtor fees. This will leave them with a whopping $1,730 check for paying $32,400 in mortgage payments not including PMI, homeowners, and taxes. Sure, they will also have got a small tax deduction during that time...but I think they might have been able to rent and save more money.
Just as a matter of opinion, look at your amortization schedule and consider dropping some more money into your mortgage monthly. Maybe you can pay off the first half a bit quicker than in 20 years then :-)
Thursday, March 27, 2008
Steelers decide picking Booger a bad idea
I couldn't resist the title based on these headlines. The Pittsburgh Steelers signed Anthony "Booger" McFarland then choose not to keep him after he flunked a physical. Maybe the Booger will be picked elsewhere.
Wednesday, March 26, 2008
Savings Account Interest Rates keep getting slashed
Wow...this week my savings account at HSBC had its interest rate slashed once again. Here is part of the letter entitled "A Personal Message from Our Executive Vice President regarding Your HSBC Direct Account."

In these challenging times, having a savings plan is more important than ever. At HSBC Direct we are committed to helping you with your savings goals by providing the best rate we can.
As you are undoubtedly already aware, there has been a general trend of reducing interest rates in the U.S. market over recent months. These changes have been influenced by the Federal Reserve moving its target interest rate down in response to developments in the economy and financial markets. Last week the Federal Reserve again reduced this key rate, by 0.75% to 2.25%.
At HSBC Direct we review our rates regularly in the context of market conditions, the federal funds rate and the overall economic environment to ensure we are providing you a competitive rate at all times. Following a further review of all of these factors, we have reduced our Online Savings Account rate by 0.50% to 3.05% APY* effective 3/20/2008.
I wonder what makes this message "personal?" Later, Mr Kevin Martin, the supposed author of this email, states:
The good news is, you’re still getting a competitive rate — 7x the national savings average.
Well, gee Kevin...that is great news! When I signed up for HSBC Direct it was the promise of 5.05% interest rates that had me create an account. Meanwhile, I am paying 5.875% on my mortgage to your company. Since you dropped my interest rate down 2% now, can I have a 2% drop on my mortgage interest rate in the name of fairness? How about just a 1%? Since there is a "a general trend of reducing interest rates in the U.S." I think I would like to join in this trend with my debt as well :-)
Unfortunately, HSBC is still #3 on the bankrate.com list for savings account interest rates in my area. All I know is that HSBC is not gaining my customer loyalty through their continuous reaction to the market. I guess I would have been liked to been told at the beginning that the interest rate was going to track near to the fed's rate directly. That way a fed rate increase would allow me to immediately also see an increase in my savings percentage.
Of Car Seats and Strollers
Heather and I have been more intensely researching and purchasing baby items now. With Anna, we were much more aggressive in purchasing but with our next little girl, we had many of the things we needed. We have thus far bought a BOB Revolution Duallie and a Maclaren Twin Techno stroller.
After having purchased the car seat adapter for the BOB, we now are considering what to do about getting a car seat that fits. See, we have the Chicco KeyFit Car Seat and only the Graco SnugRide, Graco SafeSeat, Peg Perego, and Britax Companion car seats fit in the BOB car seat adapter. At first, we both thought, let's just buy a second car seat for our second car and be able to use that also in the BOB stroller. But, one glance at the Consumer Reports Infant Car seat ratings last night and we both agreed that wasn't best. Why? Because our less than 2 yr old Chicco KeyFit car seat scored a whopping 88 out of 100 on their ratings while the next closest was the Britax Companion at 77 and Peg Perego at 76. The Gracos were further down the list with the SnugRide at 74 and SafeSeat at 72. The Chicco was the only car seat to score above a 77 and it did so with an 88!
So, our plan changed. We probably will borrow/buy a new KeyFit base for the second car and borrow/buy a used Graco SnugRide just for the couple months its needed with the BOB.
As for the Maclaren, it claims to support newborns and using Viewpoints, I was able to verify that this actually works.

Monday, March 24, 2008
Happy late Easter!
Its a day late, but Happy Easter! As my last post pointed out, Heather and I spent our Easter weekend in Ponte Vedra as has been her family tradition since before Heather was born.
As of yesterday, Heather is 35 weeks pregnant and looking/feeling great. Since she was so far along in her pregnancy, we decided to fly instead of drive since her doctor wanted us to stop every 90 minutes for her to stretch if we drove. We took Express Jet direct from Raleigh to Jacksonville, Florida. Based on this one experience, I highly recommend Express Jet. They give you a healthy meal and drink on every flight with $1 beers and $3 wine and XM radio to entertain you. They are also cheaper than their competition. We enjoyed it.
When we got into Jacksonville airport, we picked up the car we had rented through Hertz. Thinking, I don't want to carry down the car seat, we rented one for about $30 for the 4 days we had the car. One thing that I found difficult was that the car seat was just tossed in the back. It looked as if it had just been cleaned (it was covered in plastic) and it was a Graco which I had no experience with. So, in the parking garage (the rental cars in Jacksonville are across the street in a parking garage) I had to figure out the new car seat and the car. It took me about 15 minutes since it was a Toyota Corolla (which Hertz claims is a mid-size car like a Mazda 6?) which I am familiar with and the car seat was already set up for Latch and Tether. I used Latch and Tether as well as seat belt just to be safe.
Is it too much for the rental car company to put in the car seat? Is it for liability reasons? Frankly, I would be tempted to sue them anyway was something to happen to Anna and the car seat found to be the problem. Why? Two reasons. 1) It was an old car seat. 2) They put me in a situation where I could not have the same success I can at home. I don't know the car seat or car....also, here in Raleigh, the fire stations check the car seat installations for you and will ensure they are properly in. Without having any experts available to check, they are putting me at a disadvantage and charging me for it.
Ponte Vedra was great once again as was spending time with Heather's extended family. I hope you all also had a great Easter!

Wednesday, March 19, 2008
Ponte Vedra Beach Resort
Heather's family has been staying at the Ponte Vedra Beach Resorts just south of Jacksonville Florida for the past 30+ years every Easter. The resort lists the event as their family reunion...but in reality it is so much more than that. Heather's family spends time together through this interaction in a way that I can only hope we are able to maintain throughout the years. The different families spend time together intentionally and that has led to a lot of fun interactions. You can see my brother-in-law Kevin trash talking my 16 year old cousin, for example, on Facebook.
As a kid, we didn't have family reunions. Sure, we got together with family consistently at Christmas or Easter...but those were often just a short lived couple of hours. I fondly remember a family reunion of sort with my mom's side of the family as we all got cabins somewhere and spent time together. I remember playing basketball with my Uncle Paul...but that was now so long ago. Unfortunately, through moving away from Pittsburgh I have lost touch with so much of my own family. The only one I still keep in touch with is my Uncle Paul, who since Anna was born has visited us about four times. In the past couple days, my Aunt Carol and I have again been in touch exchanging emails. Beyond that, there is no and never has been to my knowledge significant regular time spent together.
Heather's family is fortunate to be able to spend that time together. Most of Heather's father's siblings and their families spend Thursday to Monday every Easter at Ponte Vedra. Since I have joined the family, they have done nothing but welcomed me into their family and treated me like I belonged there. We always look forward to this trip every year and I am happy that the time has come again this year. What is really neat is that Heather's cousins are some of the closest family we have. Two of her cousins have been having kids at the same time as us. You can see pictures of Heather's cousin Lauren and daughter Katrinca visiting when Anna was young and was the catalyst for her beginning to crawl. We also visited them this past November and had a great time. Another cousin has lent us maternity clothes and gear like a playmat and excer-saucer.
Ponte Vedra is not the only time we spend with Heather's extended family. We used to see them at Thanksgivings and Christmases, although since her grandfather passed on that does not happen anymore. Since then, there is a big gathering every New Year's. Also, the female aunts and cousins all go to NYC every summer together and see a show and shop. We also have traveled to Europe together and some of the other family has traveled to New Zealand and other places together. But, none of those are as significant as Ponte Vedra. I am not sure those trips would happen without Ponte Vedra as I really believe that these relationships would not be nearly as strong if this "family reunion" at Ponte Vedra did not happen every year. This is why we really look forward to it and why we are thrilled to be there once again this Easter.
Tuesday, March 18, 2008
Tonight's date night with Anna
Tonight, Anna and I ate at the delicious Andy's Cheesesteaks and Cheeseburgers. Then, we took a trip to Target to return a bathing suit and buy some goodies for our upcoming trip and plane ride. We bought Crayola color wonder markers and paper, a beach ball, and a portable DVD player. 
Interestingly enough, all the inexpensive (<$100) portable DVD players at Target have horrible ratings. So, perhaps its just that expectations are too high?

Monday, March 17, 2008
Emergency Funds
I have been thinking a lot lately about our emergency fund. I have heard people say two things, "3-6 months salary" and "3-6 months living expenses." Most will admit that the more risky your income is, such as if you are purely on commission or a contractor, you should have closer to 6 months instead of 3 months. I think that the living expenses is the best way to go, since its not important to continue saving when you have such an emergency. But there are other factors I have been thinking about...
1) Include money to break out of contracts. Some of our monthly expenses are contractual and it takes some money to break out of those contracts. For example, my Sprint PCS 2 year contract has a fee of $250 to break out of it. Our pool contract does not allow you to break out of a given year's payments unless you sell your home. If you lost your job and are having problems finding a similar paying job, you may need money to break out of the contracts so that your new budget does not have to have those large expenses.
2) Know that COBRA will raise the cost of health care. Trying to find the typical cost of COBRA, I found one article claiming it was $1498 per month and another claiming $600 per month for a family. Frankly, I trust Bankrate.com and the second article more.
3) Continue to save for car expenses at a lower rate. If you don't have a car loan and are saving to pay cash for your cars, you should continue to save for that next car but perhaps at a much lower rate. While retirement, college savings, and investments should probably be slowed, your car is still a ticking time bomb. Do you need as nice of a car as you were saving for? Perhaps not.
Sunday, March 16, 2008
Breakfast at the Burckarts
Breakfast here has gotten pretty predictable for Anna and Heather. Anna eats a banana and a half of a waffle while drinking her milk. Heather has also been eating waffles and cannot drink juice since Anna will want it. :-) So, since everyone has been enjoying my waffles, I thought I would put down my recipe here. We make these waffles and store them in the freezer in a big zip lock bag. When Heather or Anna go to have some, they just take them out of the freezer bag and put them into the toaster oven. Here is my recipe:
3 egg yolks
3 cups skim milk
3 cups all-purpose flour
1 and 1/2 tbsp of baking powder
3/4 tsp of salt
1/2 cup of vegetable oil (under if anything)
1 tbsp honey
1 tsp cinnamon
Mix all that together in a large mixing bowl.
Stiffly beat 3 egg whites in a separate bowl. Fold that into the mixture in the larger bowl.
Make your waffles. If you are freezing, let them cool and put them into a ziploc freezer bag (gallon size will be needed). Make sure you take out the air in the bag to keep out freezer burn.
Wednesday, March 12, 2008
Buy Last Year's Baby stuff brand new discounted
For those of you who are not "in the know" about this deal for whatever reason, you can buy last year's model stroller, high chair, etc for steeply discounted prices. There are many sites that offer these older models for good discounts. Heather and I just purchased a 2007 brand new stroller for $110 less (27.5% off!) than Babies"R"Us offers from a site called Baby Dealz. Yes, the "z" in "Dealz" is sort of lame and the site may not be as spiffy as Babies"R"Us or Target...but the prices are phenomenal. Also, we got free shipping on our stroller, ordered it Sunday and it arrives today according to UPS. And, since the site accepted PayPal, I didn't even have to worry about them having my financial info. Also, they are a Yahoo! store which helps me trust them a bit more. In this case, it seems to have worked out...although I won't know for sure until we get the delivery later today.
One thing I have noticed about these deals is that they get worse as the companies have less stock. You can see on Baby Dealz that some of their 2006 models are less discounted than the 2007, and some of the 2007 colors are more discounted than others. I assume this all depends on how much stock they have of a particular product. So, I am guessing the best buys come when their stock is at its peak which would be shortly after the new models come out.
Other sites I have browsed (but never bought from) that I keep links to include:
Best Buy Baby
Albee Baby
BabyRide.com
CSN Baby
D!mart stores

Monday, March 10, 2008
Sunk Cost Dilemma -- "Live like no one else today..."

"... So you can live like no one else tomorrow." Is a good quote used often by Dave Ramsey. I am not sure if he originated it, but I do like it. Dave Ramsey is one of the most vocal anti-debt voices out there in the world. What amazes me is that those who are vocally anti-debt like myself, are often those who were on the brink of serious financial disaster at some point. But some who were there get right back in debt.
My new theory is that there are two reactions to being close to financial ruin, fight back and change your ways completely or do just enough to survive another day. Those who fight back are often the ones who change their lifestyle enough to pull out of debt and if it was a serious amount of debt, they did that long enough that they hate debt if for no other reason but because they had to live a very limited lifestyle while getting out of debt. Every financial adviser has a similar blueprint as to how to get out of debt which goes something like this:
1. Establish a budget that minimizes expenses and maximizes debt payments.
2. Save a $1000 emergency fund so you don't pile emergencies on credit cards.
3. Pay off unsecured debts using either the debt snowball (smallest first then put all that money on the next largest) or by paying off the highest interest rates first.
This simple formula can be seen in the Wall Street Journal, Washington Post, New York Times, USA Today, by Financial Advisers like Fidelity Investments, by Dave Ramsey, and through ministries like Crown Financial Ministries. Whats amazing is the difference of what you do afterwards. Do you pay off secured debts or not?
Secured debts are those which have some backing collateral, like a car or a house. The difference between some of the advice and others is whether they suggest you pay off secured debts to eliminate the risk of debt in your life or not. The aggressive financial adviser wants you to start pouring the money into their service and quickly will point out that you can get a higher rate of return (they may quote anywhere from 8-14%) from mutual funds than your interest rate on your secured debt (4-7%), so its not important to dump the extra money into your secured debt. Others, like Dave Ramsey and Crown would point out that this is known as the sunk cost dilemma.
The sunk cost dilemma is an economic principle that points out that people who have already committed to one path (like paying a car loan, student loan, or mortgage) will choose to stay on that path rather than review if this really makes sense. For example, would you borrow against your house to put the money in the stock market? If so, you are a big risk taker, most would not. Well, this is essentially what you are doing with a mortgage if you are putting money into the stock market instead of paying off your house.
Dave Ramsey and Crown would also point out Proverbs 22:7, "The Borrower is slave to the lender."
The bottom line is, "Live like no one else today." Don't fall prey to the sunk cost dilemma. Pay off the secured debts as well. Then, when you have no debt and can pay yourself a lot more, you will "live like no one else tomorrow."
Saturday, March 08, 2008
Yay rain!!!
We are in desperate need of rain...and finally getting some. Yay rain! According to the WRAL Drought Monitor, we are still 8" behind on rain since January 1, 2007. Falls Lake, which is Raleigh's water source, is finally catching up due to a soggy week. As you can see from these Lake level graphs, the lakes are now up above where they were in September...but not where they need to be to be out of the drought. According to this page (chart shown above) on the lake levels, Falls lake is at 247.3 ft and normally should be at 251.5 ft.
As for us, we are praying the rain keeps coming. Anna is ready in her raincoat:


Friday, March 07, 2008
Gaucho Restaurants in London
This past week I took a 5 day vacation with my brother-in-law Kevin to London during his Spring Break. We had a great time. The most significant and amazing thing to me was this meal I had at Gaucho Restaurants. Gaucho is an Argentinian Restaurant. We went to the one around the corner from our hotel, Le Meridien Piccadilly to the Gaucho Piccadilly. We found this restaurant thanks to the Frommer's London Day by Day guide who listed this as the best beef and was a very close restaurant to our hotel.
Unfortunately, we didn't have reservations but thanks to the fact we came on a Monday night and early for those in the UK (7 PM), we were welcomed in to sit right next to the main cook and watch him behind the glass. It may sound like an ideal seat until you realize how hot it was. The cuts of beef were fabulous and watching this guy cook 20-30 steaks/filets at a time with fish, chicken, and lamb was amazing. I ordered the Bife de Lomo, which was their tender filet. I ordered a 400g medium, my standard when not knowing what to expect and since I was having trouble figuring out the sizes combined with a hunger from walking nearly 10 miles in 2 days plus only eating a ham and cheese sandwich since breakfast. Needless to say now that I can do the conversion, it was the biggest filet I ever had. I watched the chef cook my steak, very slowly as all of their steaks are cooked. It was amazing to watch him manage so many steaks and doing them to order purely by feel, no temperature taking here.
When I got the steak, I cut into it and saw that it was very red. By looks alone, it was definitely a medium rare if not rare. But, I then noticed there was no blood coming out...my plate was clean. I tried a bite and the steak melted in my mouth, no chewiness for it being so red, and it was warm throughout. The steak was marvelous, I enjoyed bite by bite but unfortunately could not finish it all as it was enormous. Both Kevin and I were amazed at the steaks, the flavor and perfection, and were both sure that this was the best steak either of us have ever had.
The one thing that lacked was the service...the people never really came by often. We think it was the worst service we had in our 5 days in London. Typically, we Americans are treated well since we tip well. But our waiter came over maybe twice our whole meal. As a matter of fact, they left us sitting there so long that we ended up getting hungry enough for dessert. I had the Banana Tres Leches and Kevin had the Chocolate Truffle Cake. Both were delicious although the Chocolate Truffle Cake came with a "créme fraiche" which Kevin and I thought was whipped cream on the plate...but turned out to be sour cream.
Saturday, March 01, 2008
Anna in a box
Early this morning Anna was dragging around an empty diaper box destined for the recycling bin, but I wasn't sure what she wanted to do with it. First, I put her in the box to see if she liked it. She sat down and was just so happy in her box. So, I cut one side of the box so she could go in and out. Within minutes she had her stuffed animals, Sammy the bear and her bunny, in the box with her enjoying their new accommodations. Before she stopped playing with the box, she closed it back up just as she likes to close doors.

Tuesday, February 26, 2008
Sick date night with Anna
Tonight Anna laid on me on the couch as we watched Max and Ruby on Noggin. She is still recovering from her stomach flu as am I, so neither of us were active. After an hour of that, at 7 PM, I asked her if she was ready for bed. She nodded and went right for the stairs, up the stairs, into her room, and onto the futon in her room to be read to before bed. I can't believe how much she has grown up to be able to put herself to bed when she is tired. Amazing...
Sickness
A couple days ago, Anna got a stomach flu that has lasted until yesterday. As of yesterday afternoon, I am now battling it. We haven't dealt with as much illness with Anna not in a day care. But, now I have it. My wonderful wife is taking care of Anna and I while 31 weeks pregnant...and is trying to keep well herself. This is why that all little things I can do to make her life easier are well worth it.
Its funny because one of Anna's favorite books is Mommies are for Counting Stars. The last page says, "Mommies take care of everybody" and I always add "including Daddy." Right now, that is very true.
Monday, February 25, 2008
Savings on cars is a great investment vehicle
In Fidelity Investment's quarterly magazine this month, they had an article entitled Rev up Your Retirement Savings. In this article, they declared that the average car loan is $479/mo and lasts 48 months based on information they had gotten from Edmunds. If people kept their car an extra year and invested that $479/mo with a 7% annual return, they would have $199,190 in 35 years. If they kept it two extra years, they would have $331,823 in 35 years. I set out to look closer at these numbers...
First, the data for their average expense of a vehicle comes from this article at msn.com called ABCs for a great car loan. That article says:
In the United States, the average down payment for a car is $2,400, the average amount financed is $24,864 and the average monthly payment is $479, according to Edmunds.com. The most popular loan term is now a payment-stretching six years. If you're "upside down" on your old car loan (you still owe money on it after the trade-in), it's no longer a deal breaker. In these days of easy credit, lenders will roll the old balance into the new. Nor are down payments de rigueur; you can finance up to 100% of the manufacturer's suggested retail price, plus taxes, tags and fees.
So, according to that the average car costs $27,264...but is 6 years and not the 4 years Fidelity uses. So, they already have a hole in their logic. Regardless, I think $27,264 is a bit high and I will use their numbers, $479 for 4 years making the total spent on the car $23,000 including interest.

By my calculations, at 4.8% this $479 payment for 48 months would let you buy $20,485 worth of a car. If I take that as your initial savings when you have a car loan and as not your initial savings when you don't have a car loan, than I can run some different numbers. SO, if you had $20,485 and got this 4 year loan at 4.8% interest but in the fifth year put all $479/mo ($5,748) towards your savings and got a 7% return, then you roughly would have $342,500 after 35 years. If you keep the car an extra year and put another $5,748 towards your savings with 7% return, you would have $430,500 roughly. If you paid off the car with your initial savings and bought a new car every 5 years, saving the rest, you would have $228,200 at the end of 35 years. That initial lump sum grows more quickly with compound interest than you can keep up. With buying a new car every 6 years debt free, you end up with $322,600 and every 7 years you end up with $390,000. All of this can be seen on the chart above.
Does this mean going debt free does not make sense when you run the numbers? Absolutely not. Because what is not shown, is the risk. Would you take a loan out at 4.8% per year to put it in mutual funds? Probably not...but thats essentially what you are doing. Because I had the spreadsheet made, I was able to play around in numerous what if sort of scenarios. What if interest rates on car loans go up or what if we hit a bad point in the economy where stocks go flat? That can't happen, could it? Of course it could and it is happening right now. In these cases, the no debt models win every time.
Feel free to email me if you want the spreadsheet to play around for it yourself...
Sunday, February 24, 2008
N&O's battle to claim its a moderate
A word to Local Raleigh News and Observer editors, since you keep insisting in your blogs that you are a moderate newspaper, perhaps you should try harder in your articles. A simple example is in today's Sunday's newspaper, where they have an article on "What makes a perfect president?" To represent local opinions, they polled 5 people, one on page 1E and four on page 2E. Overall, they had 3 democrats, two independents, and a single republican. I doubt these proportions represent a moderate viewpoint or their local target readership.
The editors at the N&O have avidly claimed in their blog that they do not have any partisan view. But they are criticized by many people. Here is a recent article where yet another reader complain of them being liberal and taking a certain stance, and their common response is, we get complaints that we are too conservative. Well, choosing this proportion with 5 people is not the way to declare neutrality. I guess if I was an editor serious about trying to take a middle of the line approach, I would have chosen two democrats, two republicans, and an independent. But, thats just me.
My favorite line was where the one opinion was that President Clinton was the ideal president. Because he is smart. Wasn't he the one who had issues with basic definitions in his sex scandal?
FMLA after pregnancy
I thought this was an interesting article on babycenter.com about maternity leave. Check out these restrictions on page 2 as to whether your employer can deny FMLA:
1) You have worked for the last 12 months and at least 25 hrs for 50 weeks in those 12 months.
2) You are in the top 10% of paid in your company
3) You and your spouse work at the same company and both request FMLA
A lot more info on the article online.
**Have no fear if you work with me, I am not considering FMLA. I was just looking this up in case a friend asks :-)
Avoid 401k loans
There were two articles in the N&O this Sunday about 401k loans. The first was about them becoming increasingly prevalent and the other was a Q&A about 401k loans.
The net of these hopefully will be that while these might be a short term option, they carry tough and long term penalties. Sure, if you have a medical emergency or may lose your house, then these sorts of loans are not bad ideas. But do not make it a habit and use it to reset their lifestyle to be realistic.
The downfalls to 401k loans include that people typically will stop contributing to their 401k while they repay the loan. Plus, the repayment of the loan is with after-dollars. So, this can be a big loss overall.
Saturday, February 23, 2008
Reset to Realism
I have been listening to the Dave Ramsey podcast for a couple weeks now and I definitely have noticed one consistent theme, which I think I will start calling, resetting to realism. It starts with a caller or individual stating they cannot afford something like paying off debt, doing something they want to do like take a vacation or buy a new car, becoming a stay at home mother, or just even survive. Dave asks them some simple questions about their lifestyle...how much debt do they have, how much is their rent or mortgage, and how much is their car loans or car worth. Invariably, it comes down to one of two major things:
1) Sell your house or car because you can't afford the lifestyle you are living
2) Pick a new job or extra work to get more money into the equation.
Then the real kicker is start living a lifestyle where you budget to live off less than you make AND stick to your budget. Give, Save, then Live.
Its a real epidemic in my generation...that is to live beyond your means. Dave often pleads with people to set a realistic budget based on what they make. But we don't want that realism, do we? Instead, we want what we can't have...and thats why so many people can't afford to do what they want. If you can't pay off your debt, maybe your lifestyle needs changed. If you can't afford that vacation you always wanted, then maybe your house is too expensive for what you make and if the vacations are really important to you, sell the house and live less expensively on a day to day basis while you save for those nice vacations.
Most callers to Dave's program have him give them the same equation. Reset your lifestyle to realism. This may mean driving a less fancy car or having a smaller or more out of the way house. Reset your budget to beneath that which you can afford...afford being that you still have the ability to GIVE and SAVE before the bills and entertainment and all of that is spent. That is what is realistic for your life. Reset those expectations and how you live.

Tuesday, February 19, 2008
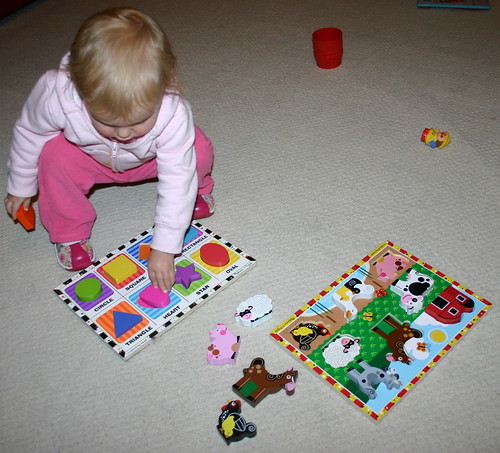
Melissa and Doug Chunky Puzzles
Tonight for our date night, we went out and bought another Melissa and Doug Chunky Wooden Puzzle at BAM!. We had the Chunky Farm puzzle and added the Chunky shapes puzzle.
I love these puzzles because they are educational (shapes and animals), provide Anna with lots of entertainment, and get her brain to think. 90% of the time, she can get the shape or animal to the right spot and about 5% of the time she can get it in to that spot. We love them and highly recommend them.
Monday, February 18, 2008
Podcasts
I know podcasts in general are kind of old news, but I thought I would share the podcasts I am listening to and some advice on how to find good ones.
1) Free podcasts only. There are so many free ones, why pay?
2) Read each episode's synopsis and skip those that seem meaningless to your life. A great example is Focus on the Family had a recent podcast on "Hope For Your Marriage After Infidelity." I don't ever plan on needing this unless I need to pass it on to someone else. Another one was from Money Girl, "Will Marrying someone with a lower credit score hurt my credit?" Another one that didn't apply to me.
3) Don't make rash decisions based on advice from a podcast. I think you can find podcasts telling you to do this or that which may or may not make sense in your life. It also may not be the best thing for you life. If you get new advice from a podcast, think and pray about it before taking that advice.
4) People you know. There are lots of podcasts from people I have never heard of. Likewise, there are podcasts from people who I have heard of in a bad way. Be careful who you listen to :-)
Here are the ones I am currently listening to in alphabetical order:
- Bill O'Reilly's talking points -- Quickly (<5 mins) Covers the major issues of the day and some good insight on them.
- Coffee Cup Apologetics -- I am still evaluating this...but it seems to have some interesting apologetics insights.
- The Dave Ramsey Show -- Talks about money management, living debt free, investing, and many other topics about personal finances.
- Denton Bible Church Recent Sermons -- Sermons from Tommy Nelson
- ESPN: PTI -- Pardon the interruption, probably my favorite sports talk analysis program.
- Focus on the Family -- Dr James Dobson and others give practical advice on marriage, parenting, and other issues in daily life.
- How to Manage Your Money -- Quick 3 minute blurbs giving practical money management advice from Crown Ministries
- InTouch with Charles Stanley -- Sermons from Dr Charles Stanley
- Money Girl's Quick and Dirty Tips for a Richer Life -- Quick (<5 mins) blurbs on finance..probably about 25% useful.
- Money Matters -- Crown Financial Ministries call in program with Howard Dayton
- NPR: Business Story of the Day
- Wall Street Journal's Your Money Matters -- personal finances
Saturday, February 16, 2008
Raleigh, #2 city for bargain house hunters
Having seen this article in Forbes, I wasn't sure that this was a title that Raleigh wanted to win. At first, I thought that whoever got this title had the housing market that had done the worst. Imagine my surprise when I saw Raleigh as #2! So, I read what made a city a bargain according to Forbes. It seems to have come down to a handful of factors and my take on why it was a factor:
1) Strong Job Growth -- Lots of people available to buy now and later
2) Foreclosures low -- No extremely cheap homes being pushed off by banks
3) Inventory is high -- Buyers can dictate terms of sale
With these factors in place, buyers can still dictate terms of sale and negotiate prices, but aren't as exposed to the economic and lending risk problems that have sunk many markets around the country.
I guess its not horrible to have Raleigh listed here...but the one I would wiling give up is our inventory being high. Interestingly enough, thats what made Raleigh #2 instead of #1:
The inventory of homes available is slightly lower than Salt Lake City (No. 1 on our list), at 14,764, despite Raleigh's larger population of 408,985 people.
Friday, February 15, 2008
10 weeks til life changes again
Yes, that is right...in 10 weeks Heather is due with another little baby girl. Our lives will completely change...again. :-) When alone, we go from man to man coverage to zone coverage. If I think about it too much, all I can think is "18 months apart..what were we thinking? Anna's isn't ready, I'm not ready, Heather isn't ready, I'm not ready" Whew! Its times like this that I have to recall one of my favorite quotes, "Fear is the opposite of faith." I don't take all fear as being that way, its much too broad of a word. But, in this case it would be worrying. Matthew Chapter 6:33-34 says
But seek first his kingdom and his righteousness, and all these things will be given to you as well. Therefore do not worry about tomorrow, for tomorrow will worry about itself. Each day has enough trouble of its own.
Read the rest of Matthew 6 to know that worrying is not a good thing. I need to practice that a bit in the next 10 weeks...until then...let's see how Anna changes. She is rapidly growing up...I don't want to hope she grows up more just so my life is easier...but a couple little things wouldn't hurt ;-)
The number 2 girl in my life
Yesterday, I came home to this picture from the #2 girl in my life:
Along with a great gift from my wife to her techie husband who works out every morning, an iPod shuffle, so I don't have to lug around my much larger video iPod when lifting weights. I am extremely blessed to have two wonderful women that I get to spend time with most every day in my life.
Last night, I cooked a dinner and the three of us had a "romantic" candlelight dinner. I put quotes around it because I am not sure any meal can truly be romantic with a 15 month old, but it was very nice. Heather and I are going to share a romantic meal this weekend while Heather's best friend, Suzanne, and her husband watch Anna. We did have a nice Valentine's day, and I hope you did as well!
Thursday, February 14, 2008
Sell Sell Sell...then Buy back if you want to
If you make an Adjusted Gross Income less than $65,100 for couples and $32,550 for singles...read on. Otherwise, this probably won't be too exciting for you. The last Bush Tax Cut to go into effect allows for those with the income levels stated above to skip capital gains taxes on the sale of Stocks, Funds, and other assets like Vacation homes so long as you have owed it for less than one year. You would pay 0% tax on the amount up to that limit...so let's say you made $55,100 as a couple...your first $10,000 would be tax free in the sale.
Don't want to sell that investment, here is a quote from the above references Forbes article:
What if you qualify for the 0% gains rate but don't want to sell your stock now? Maybe you don't need the cash. Or maybe you think that the stock will go higher? Not to worry, you can sell shares at a profit and buy back the same stock immediately, replacing your old holdings with new stock with a higher basis. (No, the "wash sale" rules, which make you wait 31 days to replace stocks, don't apply if you're selling for a gain.) "It's a great hedge against higher capital gains tax rates in the future, says Marc Soss, a tax lawyer in Tampa, Fla.
Stimulus spelled out
Wondering how this complicated rebate scheme attached to the economic stimulus plan works? This Forbes article does a good job of explaining. They break it out into 3 main rebates so long as your 2007 and 2008 adjusted gross income (AGI) is less than $75,000 for individuals and $150,000 for couples:
1) Any adult with an AGI of $8,750 for single or $17,500 for a couple will get a $300 per adult rebate.
2) Each child earns the adult $300 so long as the child is 17 yrs of age or younger the whole year (2007 is the assumed year)
3) An extra $300 per adult so long as that adult owed at least $600 in taxes. Couples would have to owe $1200 together. The example given is that if the couple only owes $900, they will only get an extra $150 per adult for a grand total of $900 back.
Here is the real crazy piece of information:

The rebate is technically a credit against your 2008 tax bill that is being paid (in most cases) as what we'll call a "prebate." This prebate is based on your 2007 income tax return. The actual credit is based on your 2008 tax return. Whichever year produces the bigger check for your family is the year that counts.
So, I guess if you can't earn the rebate on your 2007 taxes you might be able to still earn it for 2008. This is so confusing, no wonder it took Congress so long to pass it. Here is the closing line which is all too true:
Got all that? A true stimulus bill--for accountants, that is.
I guess those who have accountants or use tax software will be getting their money's worth.
Wednesday, February 13, 2008
Google Maps Street View
If you haven't checked it out, its worth a look. Google Maps added a street view tab which allows you to look at things as you would at the street level. For example, here is our house on street view (click for bigger size):
Very cool feature Google. Try it out for yourself!
BTW, this picture was taken on a Wednesday (trash day) in the afternoon (Shadows), probably 3-4 months ago (based on landscaping in our yard and leaves on the trees).
Friday, February 08, 2008
Stimulate my economy
I think its interesting where Congress drew the line in the sand between the too rich and those that need to help the economy survive. As far as I understand it, the desire is to get money in the hands of the people so that they spend it and by spending it, push more money into the economy. I think the unfortunate thing is the line in the sand. Those making more than $75,000 as a single person or $150,000 for married couples do not see a dime (depending on how the money is phased out). This says either of two things:
1. Those making above that amount do not need extra money to pump into the economy.
2. Those making above that amount would not use the money to stimulate the economy anyway.
If Congress made the first assumption, it seems that the amount was a bit low to declare that those people do not need the extra money. Those people are the ones that pump money into the expensive coffee drinks, upgrades to their homes, and other services which have a great trickle down effect. They also typically have money tied up in investments, which right now have been doing poorly and are less likely to spend their money when investments are not doing well. So, I guess I would say that giving them some extra money to pump into the system would have been a good idea.
If Congress made the second assumption, I am not sure I can argue that as well. Those people with money tend to be some of the less likely people to frivolously spend it since they have many of the nice amenities in life already. That said, they also know how to spend the money and often it can be on services rather than goods which generally keep more money in the US economy. For example, buying that expensive TV may siphon the money out of the US economy quickly as its not made in the US and the company who makes it is not often a US based company...so profits leave the US quickly. However, if you have a service like a landscaping service, everything from the plants to the laborers should be US tax paying individuals.
Either way, I guess I just wonder how the majority of people will spend this money which will only go to the lower class and most of the middle class. (All of the middle class by some definitions). Its about 1 month after the Christmas spending cycle and there is problems in the housing market. How many people will use this to help with their mortgages or pay off credit card debts racked up from Christmas? I personally hope that many will. But, that doesn't stimulate the economy.
Don't get me wrong by this posting, I don't believe the upper class at this point needs the money. I just think that the theory for how this money is going to get pumped into the economy isn't one that scales. How about tell the upper class that if they pull money out of their investments and spend it all on services, they can not pay tax on those investments. That seems like a way to get the rich to put some more money into the economy :-)
Wednesday, February 06, 2008
Write down those check numbers
As I wrote about a few weeks ago, there have been some significant changes for the rules about what documentation you must have for 2007 tax deductions to charities. Because of these rules, we have over $100 in tax deductions we will miss because we don't know the check number and we did not receive a receipt in the mail for the charity or because we know the check number but the small amount of the check does not warrant the $1 charge our bank charges per official copy of the check. Each of the amounts we did not get back were checks given to a friend raising money for a trip or for a charity. One friend's children whose father died of cancer in 2006 decided to raise money for St. Jude's. We sent them a check which was made out to St. Jude's...but did not receive a receipt and can't find the check number :-( Another friend was going on a mission trip to a foreign country through a local church. We made the check out to Providence, one of the largest churches in the area, but haven't seen a receipt from them either. There are a couple of other examples, but clearly this is our fault for not tracking check numbers early in the year. All total, we needed about 7 canceled checks but ended up only getting two of them.
While this sounds like a complaint, I did intend this to be informational for people to learn from our mistake. If your bank is like our credit union and does not make canceled checks viewable online (Bank of America makes the checks viewable online for free) or sends you canceled checks, make sure you record the check number of every contribution you make next year. If its a $250 or larger contribution, you have to have a receipt from the charity anyway. But if its smaller, write down the check number now and plan on getting that canceled check.
Subscribe to:
Posts (Atom)